A genuinely onchain attempt at a secured-credit card: USDC sits in a user-owned escrow contract, fees are almost zero (no monthly, no top-up, 0% own FX markup), virtual cards are instant, and the August 2026 $500k partner-infra hack was refunded in full plus 10%. But rewards are referral-shaped rather than real cashback, KYC is full Sumsub with 5-year retention, UK/EEA is not served, the $35 non-refundable dispute fee is consumer-hostile, and the exploit showed that 'self-custodial card' still means trusting third-party contract logic once funds leave your wallet. Reasonable as a cheap crypto-spend card for the supported 50 countries; keep card balances small.
Partner-infra exploit: outdated Rain Solana card contracts drained $500,859.22 in card balances from 1,685 Avici users on 2026-08-28 (authorization bypass: SubmitSignatures -> AddCollateralAdmin -> WithdrawCollateralAsset); full refund + 10% compensation, but no public Rain post-mortem yet.
Avici's own docs contradict each other on ATM limits: '$250 per day' (profile-verification page, DefiLlama) vs '$1,000 per txn / $3,000 per day' (fees-and-limits page).
FX cost drift: marketing says '0% FX markup' but ToS fee table shows 'currently 1%' Visa FX fee on non-USD transactions (max 'up to 3%').
+4 more red flags - expand before loading funds
$35 cardholder dispute fee in USDC/USDT, non-refundable regardless of outcome, disputes only for transactions > $30.
iOS app seller is 'Higin Inc.' rather than the legal operator Avici Inc. (ownership noise, reported).
ToS: 'Avici and Issuer reserve the right to amend these Card Terms... at any time with or without notice'; spending limits can be cut to $0 at issuer discretion.
Same-name noise: unrelated '$AVICI' memecoin ('Ownership Coins') appears in community searches.
Review
by the cryptodebitcards editorial desk · curated review · prose updated 2026-10-04 · facts as of 2026-10-04 · how we verify
Overview
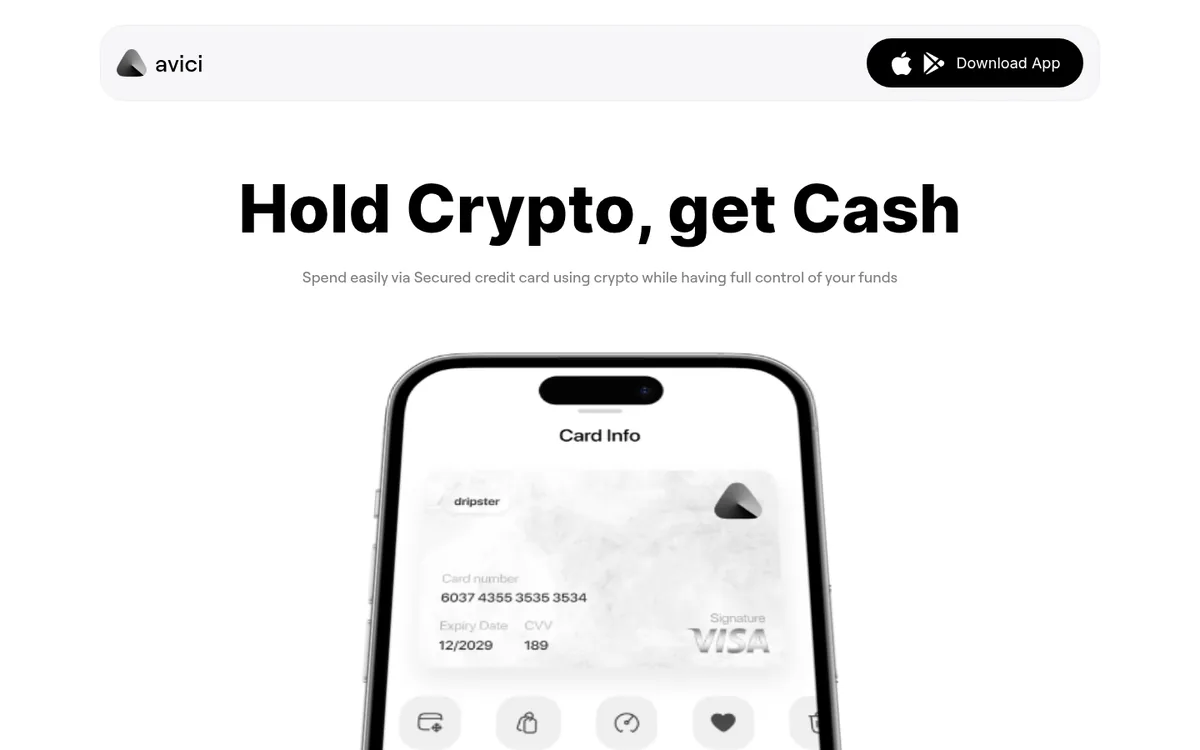
Avici Card homepage - live capture 2026-10-04
Avici is a secured-credit Visa card from Avici Inc., a Delaware C-corp based in San Francisco, built on genuinely on-chain rails: your USDC collateral sits in a user-owned escrow smart contract that "neither Third National or Avici or Visa controls", with weekly settlement and automatic deduction [1]. Spending is collateralized 1:1 with no provider-set limits - "There are no transaction limits on the card" per the fees-and-limits docs - and 0% APR [2][1]. The issuer of record is Nimbus LLC dba Third National, the same Puerto Rico-licensed Visa issuer behind several cards we track [5]. The product is live with public metrics around $73M annualized volume and 130K+ signups [1]. Custody is where nuance matters: the wallet is a Zerodev ERC-4337 smart wallet, but the August 2026 exploit showed the card spend path still trusts third-party contract logic - we classify it as hybrid [1][6].
Fees & Costs
The fee floor is close to zero: no monthly fee, no top-up or transaction fees, and no Avici FX markup - "there is no markup from Avici" [1]. The costs that remain come from the rails: Visa may charge a small 0.4-1% cross-border fee on non-USD transactions per the docs, while the ToS fee table reads the foreign exchange fee as up to 3% and currently 1%, charged by Visa with no Avici markup [1]. Card purchase fees are one-time: $15 for the first Platinum virtual ($10 subsequent), with the Signature tier at $30 first year then $20/year [1]. ATM withdrawals cost $1 plus 0.65% on Platinum and are free on Signature [1]. One consumer-hostile item: a $35 non-refundable dispute fee on transactions over $30 [1].
KYC & Onboarding
Full KYC via Sumsub with ID documents and liveness; US accounts additionally collect SSN, employer and income data [1]. The privacy policy is explicit about continuous monitoring - "We use the Sumsub AML plan to continuously monitor AML for users as well as funds on-chain" - and about US data retention of 5 years before deletion [1]. Availability covers 50 countries; the UK and the whole EEA are not served [1].
Coins & Top-up
Collateral accepts USDC with auto-bridging across EVM chains and Solana, and any token via Relay auto-swap; fiat onramp runs through Iron (Bridge.xyz) [1]. Deposits land in the user-owned escrow contract [1]. The internal contradiction to flag: Avici's fees-and-limits page says ATM limits are $1,000/transaction and $3,000/day, while its own verification page says $250/day - we record both and recommend confirming in-app before relying on either [1].
Rewards
There is no standard cashback on your own spending - DefiLlama's empty field is correct [3]. Rewards are referral-shaped [3]: per the rewards terms, you earn 2% of a friend's eligible spending for their first 90 days, and an X promo that bumps the referral rate to 3%. Welcome bonuses add $5, or $8 via referral [3]. After the August incident, affected users received full restoration plus 10% compensation - that was incident response, not a program [6].
Reliability & Red Flags
The defining event: on 2026-08-28 an attacker exploited an outdated version of Rain's Solana card-collateral contracts - adding itself as collateral admin through a faulty second-signature check - and drained $500,859.22 from 1,685 Avici users across thousands of transactions [6]. Avici restored all affected balances and added 10% compensation, and its own self-custodial wallets, EVM card balances and fiat rails were unaffected [4][6]. The same Rain infrastructure also hit Tria (636 users, $431,945) [5]. Beyond the incident: the internal ATM-limit contradiction, the $35 dispute fee, and the fact that card refunds cannot be withdrawn [1]. No additional theft reports exist in the community record [6].
Verdict
This is one of the more honest attempts at on-chain card custody - the escrow contract structure is real, the fee floor is nearly zero, and the incident response was exemplary by this market's standards [1][6]. The trade-offs are real too: rewards are referral-shaped rather than cashback, KYC is full Sumsub with 5-year retention, the UK and EEA are excluded, and the exploit proved that the spend path inherits contract risk even when collateral is self-held [1][6]. Size collateral accordingly, avoid balances you cannot afford to freeze during an incident, and check the current Rain contract version before large collateral deposits [6].
What works
Genuinely self-custodial collateral on EVM: user wallet owns the escrow contract; neither Avici, Third National nor Visa controls it
Nearly free to use: $0 transaction/top-up/withdrawal fees, no monthly fee, 0% Avici FX markup
Platinum virtual card costs only $15 one-time ($10 for further cards)
Instant virtual cards (2 minutes) usable at 100M+ Visa merchants, plus Apple Pay / Google Pay
Flexible funding: USDC native, any token auto-swapped via Relay, Solana auto-bridged, external-wallet top-ups, USD/EUR onramp accounts
August 2026 hack fully refunded in days, plus 10% compensation; FBI report filed
No standard cashback; rewards limited to referral commissions (2-3%) and discretionary promos (Korea 10% in ANSEM memecoin)
$500k exploit of partner (Rain) Solana contracts in Aug 2026 proves card-balance custody risk; no full public post-mortem yet
Full KYC via Sumsub (ID + liveness; US SSN) with data shared to card partners/Visa and 5-year US retention
No UK/EEA availability; 17 prohibited countries; US limited to 32 states
Visa cross-border/FX fee on non-USD transactions (0.4-1% per docs; 'currently 1%' per ToS)
$35 non-refundable dispute fee regardless of outcome; only > $30 transactions eligible
Signature tier carries a recurring $20/yr fee from year two ($30 first year)
Refunds processed to the card 'cannot be withdrawn to the wallet and can only be spent'
Fee reality check
Top-up fee
0%
FX fee
1%
ATM fee
0.65% + $1 per withdrawal
Fine print
Avici charges no FX markup ('Forex markups- 0%*') and $0 transaction/top-up/withdrawal fees; Visa fee applies to non-USD spend: docs note 'Visa may charge a small 0.4-1% cross border fee for non-USD transactions', while the ToS fee table reads 'Foreign Exchange Fee (non USD): up to 3%, currently 1% (Charged by Visa, There is no markup from Avici)' and Cross Border Fee 'currently 0%' (USA Notion terms: 'International Transaction: 1%'). Card purchase fees: Platinum virtual $15 first card, $10 subsequent, one-time; Signature virtual $30 first year then $20/yr; physical Platinum $50 one-time; physical Signature $75 + $20/yr from second year. Free untracked delivery 3-4 weeks; priority $50 international / $15 US. ATM: Platinum $1.00 + 0.65% (balance inquiry $0.60, decline $0.60), Signature $0; 3 withdrawals/day. Penalty-fee table (ToS, 'maximum charges that we could charge'): late payment $0 up to $40 (USA terms: up to 2% of outstanding balance), returned payment up to $29, liquidation penalty up to $35 'currently not supported'. Cardholder dispute fee $35 in USDC/USDT, non-refundable regardless of outcome; only transactions > $30 eligible; reviews up to 90 days.
Three steps, based on the operator-documented facts in this review (fact status: verified 2026-10-04):
Sign up. full identity verification is required at signup.
Top up. Native top-up coins: USDC. Minimum load: 1. Load fees are in the fee table above.
Spend or withdraw. virtual and (where issued) physical card payments. ATM withdrawals are documented - check the ATM fee rows above before relying on cash.
Check your country. Documented region: UAE, Antigua & Barbuda, Argentina, Australia, Barbados, BD, Bolivia, Brazil, Bahamas, Belize, Ivory Coast, Colombia, Costa Rica, Dominica, Dominican Republic, Ecuador, EG, Grenada, Ghana, Guatemala, Guyana, Hong Kong, Honduras, Japan, Kenya, St Kitts & Nevis, Cayman Islands, St Lucia, Morocco, Mexico, Malaysia, New Zealand, Panama, Peru, Philippines, Pakistan, Paraguay, Singapore, Senegal, Suriname, El Salvador, Turks & Caicos, TH, Trinidad & Tobago, Uganda, USA, Uruguay, St Vincent, South Africa, Zambia. Run the region checker for exclusions named by the operator.
Based on our checks as of 2026-10-04: Avici Card scores 4.8/10 in our weighted review. We logged 7 red flags (listed above). User reports and the operator background are documented with dated sources in the meta-review below.
The meta-review: what the internet says about Avici Card
We do not expect you to trust us. This review is a meta-review: below you see what other review sites claim, what users report on Reddit and forums, and who actually operates Avici Card - including the issuing structure behind the card. Every claim links to its source so you can verify it yourself. Our verdict forms from these sources plus our own fact checks - not the other way around.
What other reviewers say (1)
Heads-up: most crypto card "reviews" are affiliate content. We mark our reliability judgement on every source and include critical voices deliberately.
Avici Review - Is This the Best Crypto Debit Card for 2026? (CaptainAltcoin headline via Google News RSS; body not fetched - note the product is a secured credit card, not a debit card).
What users say (3)
Reddit, forums, complaint boards. Anecdotes, not proof - but patterns across threads are the best early-warning system this industry has.
Very disappointed with Avici. I have been waiting over a week for my refund and have already provided all the requested information, including my bank statement and new IBAN. (unverified individual claim)
Only 2 tangential posts found ('Why You Should be Paying Attention to Ownership Coins'; '$AVICI | Real On-Chain Creator Infrastructure' - an unrelated token). No first-hand Avici Card user threads surfaced; pullpush.io returned HTTP 502.
Discussion is dominated by the August incident and its refunds; no additional theft reports found.
Who is behind Avici Card?
Card programs stand and fall with their operator and BIN sponsor. This is what we could verify - with sources. Confidence: confirmed (checked 2026-10-04).
Operator
Avici (Avici Money)
Legal entity / issuer
Avici Inc. (Delaware C corp, 300 4th St, San Francisco, CA 94107); card program issued by Nimbus LLC dba Third National (Puerto Rico money transmitter, NMLS #2612780, License #TM-0207); card infrastructure by Rain (Visa principal member); iOS app published by 'Higin Inc.', Android by 'Avici Labs' (website avici.org); Nigeria marketing via BANEX Microfinance Bank Ltd (CBN-licensed); fiat rails via Iron (Bridge.xyz)
Registered in
United States (San Francisco, CA; card issuance via Puerto Rico)
Organized as a DAO with futarchy governance (docs.avici.org); manifesto dated 3 Jan 2024 signed 'Ram <ram@avici.club>'. Third National is NOT a bank - it is a Puerto Rico money transmitter acting as Visa issuer (BIN-sponsor class), which means cardholder deposits are not FDIC-insured; the collateral model shifts consumer protection to the escrow contract terms. iOS/Android publisher-name discrepancies (Higin Inc. vs Avici Labs vs Avici Inc.) are recorded as reported.
Every external source used on this page, with the date we fetched it. Methodology: how we verify. Sources disappear or change - if a link is dead, tell us via contact. Quoted text is the verbatim excerpt this review cites.
“Foreign Exchange Fee (non USD) up to 3%, currently 1% (Charged by Visa, there is no markup from Avici). Cross Border Fee currently 0%. Neither Third National or Avici or Visa controls the loan contract.”
“There are no transaction limits on the card. Visa may charge a small 0.4-1% cross border fee for non-USD transactions. ATM $1,000 per transaction, $3,000 per day, maximum 3 per day.”
“You earn 2% of your friend's eligible card spending for their first 90 days. Welcome bonus $5 after sign-up, card order and verification ($8 via referral).”
“Nimbus LLC dba Third National is licensed as a Money Transmitter by the Commissioner of Financial Institutions of Puerto Rico. NMLS #2612780. License #TM-0207.”
The mainstream choice if you want crypto spend inside a full banking app - regulated, mature, multi-plan. Crypto card payments carry no exchange fee but the plan fair-usage limit counts crypto exchanges, each payment is a taxable disposal, and the September 2026 data breach exposed identity and transaction data. Solid for banking, honest about the crypto side-feature trade-offs.
Phantom Cash finally gives the biggest Solana wallet a spending rail: a free virtual Visa paid out of a CASH stablecoin balance with Apple/Google Pay and yield on idle balances. But it is a US-only (ex-NY), virtual-only product with a USD 2,000 standard daily cap, 1.75% card funding and no card cashback - a nice extension of the wallet, not yet a full card program.
A Ledger-branded Visa prepaid card by Baanx that lets users spend from Ledger self-custody, converting crypto to fiat at the moment of purchase and paying 1% cashback in BTC (2% in BXX). Live across UK/EEA plus a 2025 US expansion, but the open jurisdiction list is login-gated and the old Ledger shop pages are dead links.
No comments yet - be the first. No account needed; the anti-spam proof runs in your browser.