The most aggressive rewards among exchange cards: 2-10% USDT cashback tiers, auto-interest on the card balance and 100% rebates on popular subscriptions - but it requires full exchange KYC and is explicitly unavailable in the EEA, and the platform carries the memory of the 2025 mega-hack it survived.
by the cryptodebitcards editorial desk · curated review · prose updated 2026-11-01 · facts as of 2026-10-03 · how we verify
Overview
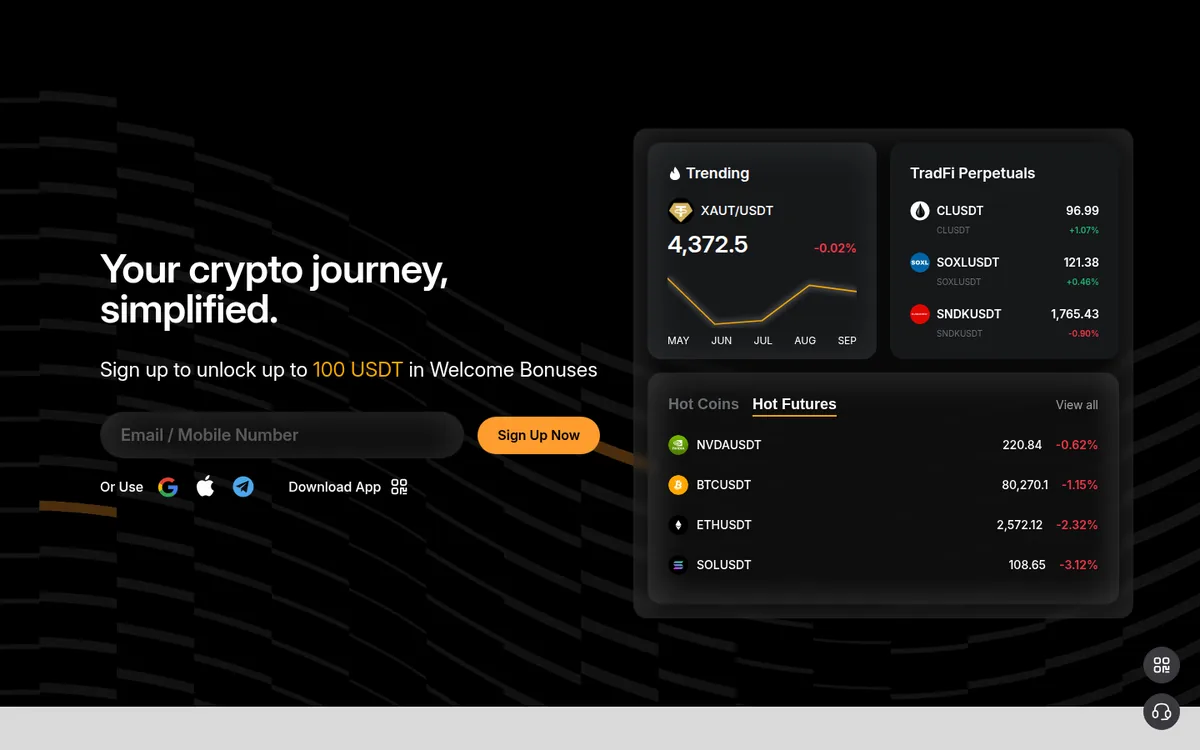
Bybit Card homepage - live capture 2026-09-20
The Bybit Card is a card program from the Dubai-headquartered derivatives exchange (founded 2018 [10]) that runs as separate regional programs on bybit.com: Australia, Argentina, Brazil, Mexico, Peru, Kazakhstan (AIFC), Georgia and an Asia Pacific program [1]. Card kind and network vary by region too - the operator's program documentation lists prepaid and credit variants across those markets. The card has no balance of its own - it deducts from your Bybit Funding Account and Flexible Easy Earn balances, spending fiat first and converting crypto only when fiat runs short [5]. Rewards are the headline: USDT cashback scaling from 2% to 10% by monthly spend, plus full rebates on selected subscriptions [4]. The catch is geographic and structural: EEA customers are explicitly barred from the global product [4], and the region is served by a separate Bybit EU Card on bybit.eu that the operator itself calls a different card [3].
Fees & Costs
The operator's fee table (updated September 2026) lists regional transaction fees on top of the network FX rate: Australia 2%, Argentina 7%, Brazil 1.5%, Mexico 2%, Peru 1% [1]. Crypto-funded transactions add a 0.9% conversion fee (0.5% in Argentina) when fiat is insufficient and crypto is auto-liquidated at the One-Click Sell rate [5]. Argentina and Brazil also levy government taxes on foreign transactions on top. ATM withdrawals cost 2% after a monthly free allowance - around the first 100 USD/EUR depending on region, with local-currency variants such as 95,000 ARS in Argentina and 550 BRL in Brazil [1]; Peru is virtual-only with no ATM support at all [1]. There are no annual or monthly fees and the virtual card is free to issue [4]. Do the math before you celebrate the cashback: an Argentine user paying a 7% regional fee is losing money at every reward tier [1].
KYC & Onboarding
Full exchange KYC is required before you can apply, including proof of address in supported regions [3]. The card's fiat currency follows your KYC country. The virtual card issues free and fast; physical cards roll out per region, with Venezuela users reporting quick activation and Apple Pay setup in practice [7]. There is no documented universal onboarding duration - the help-center flow is app-gated, and we will not invent a number.
Coins & Top-up
There is no top-up mechanism in the classic sense: the card connects to your Funding Account, where idle USDT keeps earning interest while remaining spendable [5]. USDT is the primary asset; BTC, ETH, USDC, XRP, SOL and other exchange-listed assets cover shortfalls via automatic conversion at the One-Click Sell rate plus the conversion fee [5]. Payment priority defaults to USDT, then USDC, then other assets, and is reorderable [5]. No Lightning support is documented. Minimum load amounts are not published.
Rewards
The global program pays USDT cashback in tiers that scale with monthly spending, from the 2% base tier (capped at 5 USDT per month) up to a documented 10% top tier [2][4]. A welcome package offers up to 110 USDT in cashback during the first 30 days [4]. Selected subscriptions (Netflix, Spotify, ChatGPT, TradingView and similar) earn a 100% rebate for higher tiers, inside the same monthly point cap [4]. One rule changed recently and matters: effective October 5, 2026, only transactions funded with cryptocurrency qualify for rewards - fiat-funded spending earns nothing [2]. Cashback is paid in USDT, so the reward carries stablecoin (and platform) risk until you withdraw it. The separate EU program on bybit.eu pays a 1% base rate with no monthly cap - users there report the base rate was recently cut from higher levels [9].
Reliability & Red Flags
The balance model is custodial: your spendable funds sit in Bybit's Funding Account under the exchange's terms, not in a wallet you control [5]. The platform's security record is mixed but documented - in February 2025 attackers stole roughly $1.4 billion in ETH from a Bybit cold wallet (Wikipedia's account puts the total loss at $1.5 billion in assets); Bybit covered the losses and kept operating [10]. On the card itself, a user-documented fraud report describes three unauthorized virtual-card transactions that passed without any OTP challenge, raising questions about verification enforcement on the virtual card [6]. Community reports also flag the conversion spread at settlement as the real cost driver, above the headline fees [8]. None of these are card-killers, but all of them are reasons to keep balances small.
Verdict
For active Bybit traders in supported non-EEA regions, this is one of the most aggressive reward structures in the category - tiered USDT cashback, auto-earn on idle balance and subscription rebates [2][4]. It demands full exchange KYC, its regional FX fees can exceed the rewards you earn (Argentina's 7% stands out) [1], and EEA residents must use the separate bybit.eu card instead [3]. Fund it from crypto you were going to hold anyway, and treat the exchange balance as spending money, not savings.
What works
2-10% tiered USDT cashback plus subscription rebates (100% on Netflix/Spotify/ChatGPT and more)
Automatic interest on available card balance
No annual fees; free virtual card
Instant crypto-to-card funding from the exchange wallet
What to watch
Full exchange KYC required
Not available to EEA customers (explicitly prohibited)
USDT-centric funding; other coins need conversion
2025 $1.4B cold-wallet hack (covered, but documented)
Fee reality check
Issuance
Free virtual card issuance in supported regions (physical card availability varies)
Monthly
none
Top-up fee
0.9%
ATM fee
2% after the first $100/month (Australia, AIFC, Kazakhstan, Georgia, Asia Pacific); Argentina 2% after 95,000 ARS/mo; Brazil 2% after 550 BRL/mo; Mexico 2% after $100/1,800 MXN; Peru: ATM not supported (virtual only); ATM-operator access fees possible
Fine print
Regional FX fees (official "Fees and Limits (Bybit Card)", updated 2026-09-10): Australia/Asia Pacific/Georgia/Kazakhstan (AIFC) 2%, Argentina 7%, Brazil 1.5%, Mexico 2%, Peru 1% - each on top of the network FX rate; plus a 0.9% crypto-conversion fee (0.5% Argentina) when funded with crypto. The EEA/CH program on bybit.com ended 2025-12-31 and moved to the separate Bybit EU Card (bybit.eu, FX 0.5%). ATM: 2% after a monthly free allowance (~100 USD/EUR depending on region; e.g. AU first 100 USD, Brazil 550 BRL, Mexico 100 USD/1,800 MXN, Argentina 95,000 ARS).
Three steps, based on the operator-documented facts in this review (fact status: verified 2026-10-03):
Sign up. full identity verification is required at signup.
Top up. Native top-up coins: USDT. Load fees are in the fee table above.
Spend or withdraw. virtual and (where issued) physical card payments. ATM withdrawals are documented - check the ATM fee rows above before relying on cash.
Check your country. Documented region: APAC, MENA, LATAM. Run the region checker for exclusions named by the operator.
Based on our checks as of 2026-10-03: Bybit Card scores 6/10 in our weighted review. We logged no red flags. User reports and the operator background are documented with dated sources in the meta-review below.
The meta-review: what the internet says about Bybit Card
We do not expect you to trust us. This review is a meta-review: below you see what other review sites claim, what users report on Reddit and forums, and who actually operates Bybit Card - including the issuing structure behind the card. Every claim links to its source so you can verify it yourself. Our verdict forms from these sources plus our own fact checks - not the other way around.
What other reviewers say
Heads-up: most crypto card "reviews" are affiliate content. We mark our reliability judgement on every source and include critical voices deliberately.
No third-party reviews with usable evidence found yet. In this niche that is itself a signal - most "review" sites are affiliate placements.
What users say (8)
Reddit, forums, complaint boards. Anecdotes, not proof - but patterns across threads are the best early-warning system this industry has.
Detailed real-usage guide from Venezuela: step-by-step application, activation, Apple Pay configuration and funding tests. Notes the card issuer is domiciled in Australia and cashback is configurable in USDT/BTC - documents the card as a working daily-spend rail in a dollar-short market.
First-hand Venezuela tests: fast signup and activation, easy funding, cashback up to 10%, and a physical card now offered with free issuance - users discuss how physical delivery to Venezuela would work.
A user who used four crypto debit cards as their main spending card since 2023 ranks Crypto.com, Coinbase, Wirex and Bybit based on actual results rather than marketing claims.
Virtual-card fraud report: first fraud attempt triggered an OTP (not shared), but three follow-up transactions from Brasil passed WITHOUT any OTP. Card frozen via support; user told to wait for settlement before dispute. Raises OTP-enforcement questions on the virtual card.
A user reports the Bybit Visa Card kept $237.13 locked for over a week despite the merchant releasing the pre-authorization. Post body was removed by moderators.
'The biggest trap with USDT cards right now isn't the headline fee, it's the hidden FX spread during auto-conversion at settlement. If you're in Europe, Bybit Card (Mastercard)...' - user-level warning that real cost is the conversion spread, not advertised fees; separately a Europe-based user (p9ce526, 2026-09-12) reports the card works fine after an inactivity deactivation.
EU user: 'I was using bybit eu card but they reduces the Cashback now to 1%, bitget card is now giving 3% but there is a fee of 1.7% for money exchange if you use something different than usd' - confirms the bybit.eu card is live in the EEA and its base cashback is now 1% (matches the official bybit.eu page: 1% base no cap, VIP 2-10%).
A user claims Bybit blocked their card during a margin top-up, force-liquidated them, then gave three contradicting excuses, and notes a Taiwan FSC investor warning. Post body was removed.
Who is behind Bybit Card?
Card programs stand and fall with their operator and BIN sponsor. This is what we could verify - with sources. Confidence: high (checked 2026-09-19).
Operator
Bybit
Legal entity / issuer
Bybit Fintech FZE / Bybit entity structure varies by region (Dubai-headquartered operations)
Registered in
United Arab Emirates (Dubai)
Top-tier derivatives exchange (founded 2018). Card brand: Mastercard. TWO card programs: global (bybit.com, EEA prohibited) and EU (bybit.eu, issued by Harmoniie SAS [ACPR France, CIB 17478] partnering with Moorwand Ltd under its Mastercard licence, EEA passporting). Card FAQ and fee details app-gated. Referral: 20 USDT/USDC + 10 for the friend.
Every external source used on this page, with the date we fetched it. Methodology: how we verify. Sources disappear or change - if a link is dead, tell us via contact. Quoted text is the verbatim excerpt this review cites.
“Australia 2% (On top of Mastercard's / Visa's Foreign Exchange Rate). Argentina 7%. Brazil 1.5%. Mexico 2%. Peru 1%. ATM Withdrawal Fee 2% (after the first 100 USD monthly).”
“Tier 1 (Base) 2.00% with a 5 USDT monthly cap. Effective October 5, 2026, at 10:00 UTC, only transactions funded with cryptocurrency will qualify for Rewards Points or cashback. Transactions funded by fiat balance are not eligible.”
“We require your action before Dec 31, 2025. If you are an EEA resident, you can visit bybit.eu/cards to register a new account on Bybit EU. The Bybit EU Card will be a new card on the Bybit EU site, and it is different from your current Bybit Card.”
“During the transaction, the fiat in your Funding Account will be deducted first, and when the amount of fiat is insufficient, the crypto as the payment option will be deducted.”
“The biggest trap with USDT cards right now isn't the headline fee, it's the hidden FX spread during auto-conversion at settlement. If you're in Europe, Bybit Card (Mastercard)...”
“I was using bybit eu card but they reduces the Cashback now to 1%, bitget card is now giving 3% but there is a fee of 1.7% for money exchange if you use something different than usd”
The most mature crypto prepaid card in the US - FDIC-member bank issued, $25k/month top-ups and clean tier structure - but the free tier earns nothing, real cashback requires a subscription or five-to-six-figure CRO stakes, and rewards are paid in volatile CRO.
Full KYC1.5% backphysical card
0% load · 3% FX · 1.5% back in CRO
$25,000 aggregated top-up limit per month (all tiers)Exchange 39 d ago
Gate Card exists, is actively developed and advertises the most aggressive cashback headline on this list (up to 8%), but the program is a black box: issuer unnamed, no published fees, no documented limits, regions defined only as 'non-restricted countries'. Fine as an exchange perk for heavy Gate users - hard to verify for anyone comparing card terms.
Full KYC8% backphysical card
1% FX · 8% back in points (redeemable for USDT or GT)


No comments yet - be the first. No account needed; the anti-spam proof runs in your browser.