Credit lines against your portfolio and crypto-rewards credit cards - a fundamentally different product from debit.
Short answer:ether.fi Cash is our top-rated crypto credit card as of 2026-11-07 (7.6/10), Basic KYC, 0% load fee.
cards on this page: 14 · issuing today (excl. watch list): 9 · independently verified facts: 86% · no KYC at first use: 0%
quick picks
uncapped bitcoin with the cleanest terms→Fold Bitcoin Credit Card - 1.5% BTC back uncapped via Celtic Bank, stackable toward ~4%, and the cardholder agreement lists no cash-advance facility at all
category rewards with published caps→Gemini Credit Card - 4% gas/EV/transit on the first $300/mo (then 1%), 3% dining, 2% groceries - WebBank-issued Mastercard World Elite
the highest headline rate with tier structure→Crypto.com Visa Signature Credit Card - up to 6% in BTC or CRO, tiers gated by CRO staking or subscriptions, BTC caps $250-$10,000/mo by tier - read the cap table first
The most complete self-custodial spending stack in this comparison: your own vault plus real bank rails in four currencies (ACH, SEPA, GBP FPS, Swiss IBAN), 3% ETHFI cashback on the first $2,000/mo with Category and 5% travel boosts, KYC light in practice (ID + liveness; proof of address only on request - verified first-hand September 2026 with a Paraguayan cedula and a German passport) and an uncapped public affiliate program. The documented risks are real: interest from the first tap in Borrow Mode, liquidation risk, the November 2025 fraudulent-card incident with promised refunds, a protection program still marked not yet live that excludes compromised keys, and cashback now locked in volatile ETHFI instead of instant USDC.
The most complete stablecoin-spending account on the market: US/EU virtual bank accounts from anywhere, Visa Platinum cards with real 1.5% USD cashback on the free tier, instant cashback and no spending caps. Full KYC and a young operator are the trade-offs; the paid tiers only make sense for heavy spenders.
Full KYC1.5% backphysical card
0% load · 1.5% back in USD
Spend up to whatever is in your wallet - no hidden monthly spending caps (Premium cap <= $10,000/mo, Private <= $40,000/mo apply to cashback earn rates, not spending)Neobank 8 d ago
The cleanest bitcoin-rewards credit card structure documented: flat 1.5% in BTC uncapped with no annual fee, up to 4% for engaged users, issued by Celtic Bank under Visa. It is a credit product - VantageScore-based checks, bureau reporting, and variable APR 20.49-29.44% on carried balances.
A premium U.S.-issued charge-style credit card (Visa Infinite) for internationally mobile high-net-worth individuals with assets at U.S. banks/brokerages - NOT a crypto card: no crypto funding, no crypto wallet, and crypto purchases are explicitly prohibited. The only crypto connection is investor-side (Galaxy Ventures led the Series A). Strong points: 0% FX, 0% APR charge model, credit lines up to $200,000, fully published fee tables, Priority Pass and a 24/7 WhatsApp concierge. Weak points: $300/year with no cashback and unpublished point values, full KYC with a high U.S. asset bar ($50k-$150k), 16-country residency blacklist (incl. India, Turkey, Vietnam, Israel), invite/partner-gated distribution, binding arbitration in Puerto Rico, and an issuer ('Third National' = Nimbus LLC dba, PR money transmitter per our verified 2026-10-03 crosscheck) whose legal name Karta's own materials never spell out. Excellent niche product; irrelevant for spending cryptocurrency.
A credible, well-backed self-custodial spend card with genuinely low fixed costs ($0 monthly/issuance/shipping, 0% APR) and true on-chain collateral custody in smart contracts. But it is not a privacy product (full KYC with SSN/national ID, GLBA data sharing), the rewards program is opaque (earn rates only in-app, statement-credit redemption at 70% of face), international FX is 'up to 3%' with a 1%-vs-2% disclosure conflict on the US side, and spending limits can be cut at Rain's sole discretion - with liquidation possible 'without prior notice'. Best for AVAX/stablecoin holders in the US (partial) and Latin America/Caribbean who want to spend against their stack; not for no-KYC users, and international terms (1-day payment window) behave much harsher than the US 21-day credit cycle.
The most generous crypto-rewards credit card in the US market - up to 6% back in BTC or CRO with no annual fee - but the best rates require CRO staking or a Level Up subscription, BTC earn is capped by tier, and it is credit (with bureau approval), not a debit card you can top up with crypto.
The most aggressive yield+cashback package in the crypto-card market, from the USDe team itself: virtual Visa with 4-5% cashback and up to 6% p.a. on balances, near-zero fee stack (no FX markup, no monthly, free issuance), self-custodial wallet, live in 48 countries across LatAm/Caribbean/Asia-ME/Africa/Oceania. The catch: rewards are paid in AVAX, are explicitly discretionary and tier-gated (Pro/VIP via limited referral-based spots), spending limits are opaque and collateral-driven, and the card is secured - your own collateral can be liquidated if a charge goes unpaid past one day or your collateral value drops. Only weeks old; no track record of its own. Strong spend-card pick where available; treat the yield as promotional, not contractual.
A US credit card on the American Express network paying up to 4% back in Bitcoin, issued via Cardless and gated behind a Coinbase One subscription. Evidence is press-grade only - the operator's own pages are unreachable from our IP - so treat every detail as unverified.
Hyperbeat Pay is the card of the Hyperliquid ecosystem's yield layer: a Visa credit/debit hybrid where a self-custodial smart wallet (ManagementAccount) settles spend from your beatUSD/USDC balance or JIT-borrows beatUSD against BTC/ETH/SOL/HYPE collateral in dedicated Morpho markets - spend without selling, audited by Zellic/Nethermind, issued by Third National under Visa. The mechanics are genuinely novel (on-chain settlement, user-set operator allowances, timelocked withdrawals) and self-custody is real. The weaknesses are transparency and reachability: no public fee schedule or cardholder agreement (fees only via DefiLlama), cashback token (WHYPE) not documented, a template artifact from ether.fi in the legal terms, an operator entity with no published incorporation, and a cashback model whose headline 3-12% tiers demand $1M-50M monthly trading volume - the realistic everyday rate is 0.2-1.0%. Strong for active Hyperliquid traders; ordinary spenders get a thin-rewards card with undocumented fees.
Gate Card exists, is actively developed and advertises the most aggressive cashback headline on this list (up to 8%), but the program is a black box: issuer unnamed, no published fees, no documented limits, regions defined only as 'non-restricted countries'. Fine as an exchange perk for heavy Gate users - hard to verify for anyone comparing card terms.
Full KYC8% backphysical card
1% FX · 8% back in points (redeemable for USDT or GT)
The most regulated issuer context for a crypto-rewards credit card (NYDFS trust, WebBank-issued Mastercard World Elite): 4% gas/EV/transit, 3% dining, 2% groceries, 1% elsewhere, no annual fee, rewards in BTC or 50+ cryptos. It is a credit product (bureau approval, no crypto funding), US-only, and the issuer carries a 2025-2026 withdrawal-security-hold complaint pattern at the exchange level.
A genuinely onchain attempt at a secured-credit card: USDC sits in a user-owned escrow contract, fees are almost zero (no monthly, no top-up, 0% own FX markup), virtual cards are instant, and the August 2026 $500k partner-infra hack was refunded in full plus 10%. But rewards are referral-shaped rather than real cashback, KYC is full Sumsub with 5-year retention, UK/EEA is not served, the $35 non-refundable dispute fee is consumer-hostile, and the exploit showed that 'self-custodial card' still means trusting third-party contract logic once funds leave your wallet. Reasonable as a cheap crypto-spend card for the supported 50 countries; keep card balances small.
Genuinely novel onchain-credit card: your deposits sit in the audited Exactly fixed/variable-rate lending markets earning variable yield while acting as collateral; Pay Now debits your balance, Pay Later borrows fixed-rate on-chain and repays in up to 9 installments every 28 days - all at 0% APR with the cost embedded in the fixed borrow rate (optional origination fee). Self-custodial smart-account wallet (passkeys), free virtual Visa Signature, instant issuance, Apple/Google Pay. Weak spots: no purchase cashback (only capped promo campaigns), 1.5% FX + up to 1.5% cross-border on the international card, virtual-only, full KYC, issuance concentrated in LatAm/Africa/Asia + 31 US states (not Western Europe/UK/Canada), and protocol exploit history means collateral is exposed to smart-contract risk by design.
A real, documented, collateral-backed Visa credit card from a funded ($12M) crypto-native team - the most complete legal/fee/cashback disclosure set of any Rain-stack card reviewed so far. But the fine print matters: FX and ATM fees are open-ended 'up to' numbers, cashback is a non-guaranteed vendor promise with lagging, discretionary distributions, spending limits can be cut to $0 without notice, issuance is effectively ~7 countries (not the advertised 150+), and the shared Rain top-up infrastructure was exploited in August 2026, hitting 636 Tria cardholders for $431,945 (refunds committed). Keep only needed funds in the card balance and treat the cashback program as discretionary.
Full KYC1.5% backphysical cardverify
1% load · 3% FX · 1.5% back in USDC and/or USDT (chosen by Tria; distributed on Ethereum, Polygon, Optimism or Arbitrum)
14 credit products define this page, and they split into two camps: US-issued credit cards financed by the exemptions that make US rewards possible (the issuer banks - WebBank, Comenity, Celtic - sit under the $10B cap threshold [7]), and charge-style credit products from other regions where a custodial balance replaces the credit line. In both camps the reward programs price against uncapped interchange. 86% of the set has independently verified fee data - the highest in the market, because issuer agreements are written documents rather than marketing pages.
The cash-advance economics that separate purchase cards from cash tools.
What the underwriting changes
Everything about the product's durability traces to the issuing bank. The credit relationship belongs to WebBank, Comenity or Celtic Bank [1][2][4] - not to the crypto brand whose name is on the card. Practically, this means the dispute process is a bank process with defined timelines [5][6], the APR terms are regulated disclosures rather than app copy, and program changes touch the rewards layer while the credit layer keeps its terms. The 2023-2026 history of reward repricing across the sector supports the same conclusion from the other side: programs changed, credit relationships persisted.
1.5% USDC and/or USDT (chosen by Tria; distributed on Ethereum, Polygon, Optimism or Arbitrum)
-
1%
3%
3%
Apple + Google
Live values from our database - details and caveats in each review. "-" = not published by the operator.
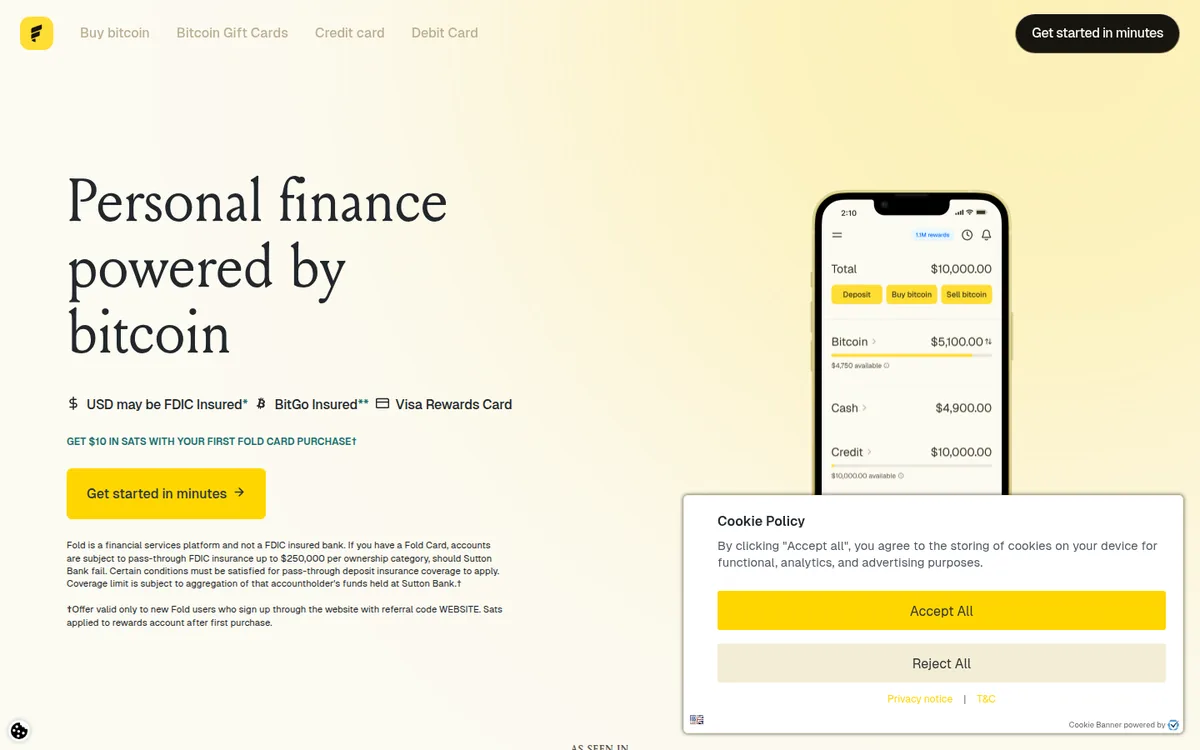
Fold's Bitcoin Credit Card page, live capture - the Celtic Bank product with no cash-advance facility and uncapped BTC earn.
The cash-advance line is the honesty test
Read the cash-advance row before any reward row. Gemini: $10 or 3%, 29.49% variable from transaction date [1]. Crypto.com US: $10 or 5%, 32.49% variable [2]. Fold's Celtic Bank agreement: no cash-advance feature listed - the account may be ineligible entirely [4]. The pattern is consistent with mainstream credit economics: cash advances carry no grace period, and on a $500 advance the fee plus daily-pro-rated interest compounds immediately. A card whose rewards look generous but whose cash-advance terms are punitive is a purchases-only instrument - treat it as one, and route any cash needs to a debit product (the physical cards hub covers ATM economics).
Rewards: flat, capped, tiered
The three structures map to three user profiles. Flat uncapped BTC (Fold) rewards consistency: the 1.5% base applies to every eligible purchase, the bonus mechanics reward statement discipline, and the upside is bitcoin's [4]. Category caps (Gemini) reward routing: gas, EV charging and transit to the capped card, dining to the 3% line, everything else to whichever card's base rate wins [1]. Tier gates (Crypto.com) reward commitment: the staking or subscription buys the rate, and the BTC caps - $250 to $10,000 monthly by tier [2][3] - define where commitment stops paying. The cashback calculator prices your actual profile across all three structures.
Warning: Reward rates are program terms with explicit change clauses - Fold's own agreement reserves the right to cap or limit categories and rates [4]. The 2023-2026 sector history is one-way repricing. Convert rewards on a schedule, keep balances small, and treat any "up to" as a tier table you have not found yet.
The liability difference, precisely
The chargeback framework is the credit card's structural advantage over every prepaid product in this market: disputes go through the issuing bank under defined error and fraud procedures [5][6], with liability limits that do not depend on the program's goodwill. For large purchases, travel, or anything with a delivery risk, that framework is the product. The trade-off is underwriting - a credit pull, an APR regime if balances carry, and the discipline the cashback hub warns about: a 4% reward that turns into a carried balance at 29-32% APR is a negative-yield instrument.
The consumer-reference layer is worth naming because it is the part most users never read: billing-error procedures with defined windows, dispute timelines the bank must follow, and fraud liability caps [5][6]. None of this exists in the prepaid world, where protections depend on the issuer's terms. When the same purchase can run through either product, the dispute framework decides - and that is before considering the interest mathematics, which is where the prepaid product's simplicity becomes its advantage: no APR regime means no carried-balance trap.
The EU-shaped hole
Why no European crypto credit card exists is the instructive negative. The EU's interchange regulation caps credit-card interchange at 0.3% [7-context], which removes the financing that makes uncapped US rewards work - a EU issuer would fund rewards from FX spread, subscriptions or token issuance, and no program has published that math. Combine that with EEA consumer-credit licensing (a regulated lending product under national rules) and the result is structural: the credit lane stays American until someone solves the financing question. For EU users, the closest functional substitute is the collateral model - the self-custody hub covers borrowing against your own coins without a bank in the loop.
Choosing from the set
10 of the 14 products carry ongoing rewards, 8 publish caps, and 9 charge no annual fee. Flat-BTC accumulators: Fold, with the payoff-bonus stack [4]. Category optimizers with domestic spend: Gemini's published caps [1]. Tier players already in a token ecosystem: Crypto.com's structure, with the cap table read before the headline [2]. Whichever fits, run the profile through the cashback calculator with your real monthly numbers - the caps make flat comparisons meaningless. And the structural note that closes every credit decision: the reward is the visible half of a product whose other half is the APR regime - which is why the ranking here scores fees and reliability alongside the earn.
Why do crypto credit cards exist at all - why not just debit?
Interchange economics and liability law. Credit products sit outside the debit interchange cap discussion entirely [7], so issuer banks can fund richer uncapped rewards; and credit cards carry dispute and chargeback rights under US credit rules that prepaid cards largely lack [5][6]. The credit card is where uncapped crypto rewards became sustainable - Fold's 1.5% BTC with no cap is the cleanest example [4].
Which issuer stands behind each card, and why does it matter?
Gemini's card is issued by WebBank, Crypto.com's US flagship by Comenity Capital Bank, Fold's credit card by Celtic Bank [1][2][4]. The chartered bank holds the credit relationship, sets the cardholder agreement, and carries the regulatory obligations - which means the dispute process, the APR terms and the FDIC-adjacent protections run through the bank, not the crypto brand. When the crypto company changes the rewards program, the credit relationship usually survives it.
What does a cash advance really cost on these cards?
Gemini: $10 or 3% whichever is greater, 29.49% variable APR per the 2026-04-01 agreement; Crypto.com US: $10 or 5%, 32.49% variable - both accruing from the transaction date with no grace period [see card pages]. Fold's Celtic Bank agreement lists no cash-advance feature at all - the account may be ineligible [4]. On a $500 advance at Crypto.com's terms, the $25 fee hits immediately and interest runs daily until repaid. Crypto credit cards are purchase tools, not cash tools.
How do the reward structures compare?
Three shapes. Fold: flat 1.5% BTC uncapped, with documented bonus paths (statement payoff in BTC, monthly bonus rules) toward ~4% [4]. Gemini: category structure with transparent caps - 4% gas/EV/transit on the first $300/mo then 1%, 3% dining, 2% groceries, 1% other [1]. Crypto.com: tier-gated rates up to 6% with BTC rewards capped by tier ($250-$10,000/mo) and CRO uncapped [2][3]. The caps are the real comparison - the cashback hub works the math.
Are Bitcoin rewards taxable?
The conservative US reading: a crypto reward is property received, income at fair market value when credited, then a disposal when sold. Fold's own terms acknowledge that paying a statement in bitcoin is a taxable disposition [4]. The IRS cash-rebate rule (basis reduction, not income) applies to fiat rebates [8]; crypto rewards are less clearly settled. Document your method per reward - the tax guide walks the patterns.
What protections does a credit card have that prepaid lacks?
Dispute and chargeback rights under the credit rules, billing-error procedures, and fraud liability limits - all administered by the issuing bank [5][6]. Prepaid and debit products have narrower, issuer-dependent protections. Practically: a disputed $500 purchase is a bank procedure on a credit product and a goodwill case on a prepaid product. For any spending you may need to dispute, this is the deciding difference.
Is there a credit check?
Yes - these are credit products underwritten by the issuing bank. Crypto.com's US product documents the process (card pre-qualification as a soft check, then approval) [2]. That is also why the APR structure exists at all: the bank prices the credit line, and the cash-advance APRs above are part of that pricing. Prepaid programs have no underwriting and no APR - different product, different guarantees.
Can I pay my statement in bitcoin?
On Fold, yes - and the terms state plainly that paying a statement in bitcoin is a taxable disposition of that bitcoin [4]. The +0.5% payoff bonus for paying in BTC is real economics, but it triggers the tax event every month you use it. Run the numbers with your tax treatment in mind; the convenience premium has a filing cost.
Do these cards help build credit history?
They are genuine credit products from regulated banks, so they can report to bureaus like any credit card - but terms on whether and how crypto-issued cards report vary by issuer, and none of the programs advertises credit-building as a feature. If credit-building is the goal, ask the issuer directly before applying; if rewards are the goal, the underwriting is just the admission ticket. What the underwriting also buys you: the bank's dispute framework, which no prepaid product replicates.
Why are all the credit products US-only?
12 of the programs here are US-available and the credit set is entirely US - the structural reasons are the uncapped small-issuer interchange that finances US rewards [7], the mature three-bank partner stack, and the absence of an EU equivalent after the interchange cap. A EU crypto credit product would need to finance rewards inside a 0.3% credit interchange cap - nobody has made that math public.
What happens to my rewards if the program changes?
They are program terms, not contract rights. Fold's terms state bonus categories and rates "may be capped or limited in duration" [4]; Crypto.com's history includes material reward repricing [3]. The mitigations: convert rewards on a schedule rather than accumulating, keep balances small, and re-verify terms quarterly - the check dates on each card page tell you when we last read them.