The most complete stablecoin-spending account on the market: US/EU virtual bank accounts from anywhere, Visa Platinum cards with real 1.5% USD cashback on the free tier, instant cashback and no spending caps. Full KYC and a young operator are the trade-offs; the paid tiers only make sense for heavy spenders.
by the cryptodebitcards editorial desk · curated review · prose updated 2026-11-01 · facts as of 2026-11-01 · how we verify
Overview
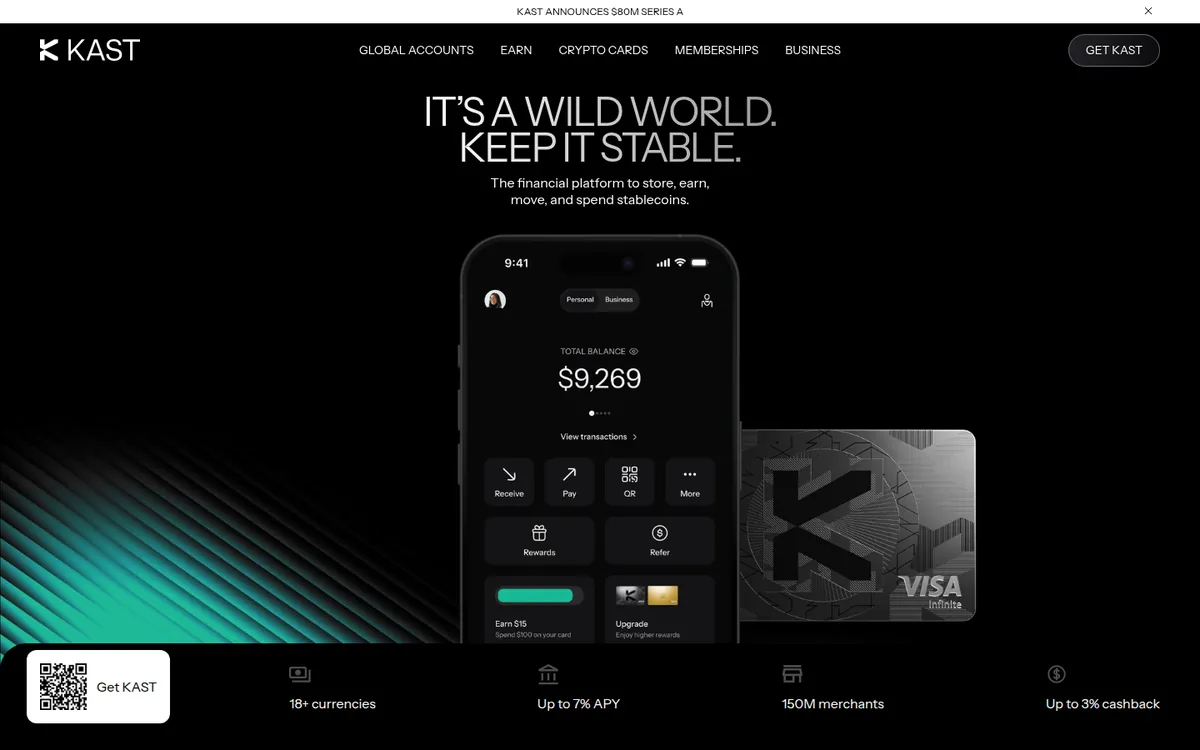
KAST homepage - live capture 2026-09-19
KAST is a stablecoin-native fintech founded in 2024 by a former Circle executive, and the top-ranked card in our database as of this review [10]. The company raised an 80 million dollar Series A co-led by QED Investors and Left Lane Capital [10], and markets Visa card spending across 170+ countries and 150 million merchants [3]. Formally, the KAST Card is a credit card under the operator's own terms - charge-style spending backed by a custodial stablecoin balance rather than a credit line [4]. Our database records the custody model as custodial, with institutional custody partners recorded for the underlying assets. The product combines US and EU virtual accounts with direct stablecoin funding, which is why it ranks so high for globally distributed users.
Fees & Costs
There is no monthly fee; the Standard membership is free [2]. Premium costs 1,000 dollars per year and Private 10,000 dollars per year [8][9]. Card transaction fees are the weak point of documentation: KAST does not publish FX percentages on any page we can access - the fee article lives in the membership help center, which blocks non-member traffic, and third-party write-ups cite 0.5-1.75% FX tiers that remain unconfirmed [5]. The one operator document we can read is an archived snapshot of that fee article (captured in January 2026, article dated December 2025), which lists 0% on USD card spend, a 2% foreign-exchange fee on non-USD spend and 0% transaction and mobile-wallet fees [5]; we treat the current FX fee as unknown rather than asserting the archived figure. ATM withdrawals cost a 3 dollar flat fee plus 2% of the amount, capped at 250 dollars per withdrawal and 3 withdrawals or 750 dollars per 24 hours [6]. A minimum top-up is not documented.
KYC & Onboarding
Onboarding requires identity verification with real-time fraud monitoring, biometric login and MFA as core features [1]. KAST is explicitly not a bank - payment, card, custody and on/off-ramp services run through licensed partner institutions [4]. Card issuance covers two free cards (virtual or physical) on Standard and a plated gold card on Private [2]. No onboarding duration is published, and we do not guess one.
Coins & Top-up
Stablecoin deposits in USDC and USDT convert to spendable USD 1:1 with no deposit fee [5]. Non-stablecoin crypto deposits (BTC, ETH, SOL) auto-convert to stablecoins at 2-5% depending on the token [7]. On the fiat side, KAST provides US and EU virtual account numbers that accept ACH, SEPA and wire transfers [3]; community reports document EUR SEPA deposits at no fee with no FX markup [11]. Spending itself is not capped: the operator states you can spend up to whatever is in your wallet, and the monthly figures in the tier table apply to cashback earning, not to spending [14]. There is no Lightning support. The top-up fee itself is not documented as a single percentage - the cost depends on the rail you use, with the crypto auto-conversion spread the most expensive route [7].
Rewards
Cashback is paid in spendable USD and credited instantly at transaction authorization [1]. The live tier table shows Standard (free) at 1.5% with a monthly eligible-spend cap of 2,000 dollars on a Visa Platinum [2], Premium at 2% with a 10,000 dollar cap plus KAST Points worth 1% of eligible spend [8], and Private at 3% with a 40,000 dollar cap plus points worth 2% [9]. Note that these caps are far lower than earlier promotional figures our dataset recorded (up to 50,000 and 200,000 dollars per month) - the live table is the figure we follow [2]. Points are not cash: the operator states KAST Points carry no assured monetary value [1]. The paid tiers only pay off for heavy spenders; the free tier's 1.5% is the honest baseline [2].
Reliability & Red Flags
The balance is custodial end to end - deposits, card spending and rewards all sit on KAST-controlled infrastructure, so counterparty risk is the operator plus its licensed partners [4]. The company is young (founded 2024) and not a bank, which matters more here than for a mature institution [10]. No incidents are documented for the card program. Two transparency issues deserve attention: the operator no longer publishes a country list despite the 170+ countries claim [12], and the fee article with the FX percentages is not publicly accessible - both make independent verification harder than it should be [5]. The wider product leans on yield marketing: the homepage advertises reward rates of up to 12% on Reserve balances, and the operator itself notes that the 2026 rate is an introductory offer that changes in July 2027 [13] - a reminder that the advertised numbers on the platform are time-limited, not structural. Community usage in MENA and South Asia is active and largely positive, with the SEPA deposit change welcomed [11]. Our fact set is verified against live operator pages as of the date above, but FX pricing is an explicit exception.
Verdict
For users who hold stablecoins and want a USD spending account with real bank rails and instant cashback, KAST is currently the most complete product we track - that is the named basis for its rank [2][3]. Keep balances to spending money: the operator is young, custodial and not a bank [4][10]. Skip Premium and Private unless your monthly card spend approaches their caps [8][9], and confirm the FX fee that will apply to your own spending before you rely on non-USD purchases [5].
What works
Free Standard tier with 1.5% instant USD cashback (Visa Platinum)
US/EU virtual accounts (ACH, SEPA, wires) from anywhere
Spending limited only by wallet balance - no monthly spend caps
Direct SOL/ETH/BTC deposits auto-converted to USDC for spending
Fireblocks/BitGo custody, $80M Series A, well-established partners
What to watch
Full KYC fintech, not a bank
Premium tiers ($1,000/$10,000 per year) priced for high spenders only
Stablecoin-centric: BTC/ETH/SOL only via conversion to USDC
Young company (founded 2024)
Fee reality check
Issuance
2 free cards (virtual or physical) on Standard; 1 free premium card on Private; plated gold card included in Private
Monthly
none
Top-up fee
0%
ATM fee
2% $3 flat + 2% of withdrawal amount (USD); non-USD withdrawals add the 2% FX fee; max $250 per withdrawal, 3 withdrawals / $750 per 24 hours
Fine print
Standard membership free. Premium $1,000/year (2% cashback + 1% KAST Points). Private $10,000/year (3% cashback + 2% points, gold card). Fee schedule (help-center fee article, Wayback snapshot 2026-01-12, article updated 2025-12-29): USD card spend 0%; non-USD card spend 2% FX fee; transaction fee 0%; Apple/Google Pay 0%; small non-USD transactions under $25: $0.10; declined transaction (insufficient balance) $0.50; ATM $3 + 2% (USD), non-USD +2% FX; stablecoin deposits 0%, non-stablecoin crypto deposits 2-5% auto-conversion, ACH $2 / FedWire $15. Snapshot tier names (Standard/Premium/Limited/Luxe) predate the current Premium/Private naming; the transaction-fee table itself is tier-independent. [2026-11-01 audit: the earlier 2% FX value had no operator source - the dossier (2026-09) records FX percentages as unpublished in served pages; reset to unknown. Third-party write-ups cite 0.5-1.75% FX tiers, unconfirmed.]
Three steps, based on the operator-documented facts in this review (fact status: verified 2026-11-01):
Sign up. full identity verification is required at signup.
Top up. Native top-up coins: USDC, USDT. Load fees are in the fee table above.
Spend or withdraw. virtual and (where issued) physical card payments. ATM withdrawals are documented - check the ATM fee rows above before relying on cash.
Check your country. Documented region: worldwide, USA, Europe (EEA). Run the region checker for exclusions named by the operator.
Based on our checks as of 2026-11-01: KAST scores 6.6/10 in our weighted review. We logged no red flags. User reports and the operator background are documented with dated sources in the meta-review below.
The meta-review: what the internet says about KAST
We do not expect you to trust us. This review is a meta-review: below you see what other review sites claim, what users report on Reddit and forums, and who actually operates KAST - including the issuing structure behind the card. Every claim links to its source so you can verify it yourself. Our verdict forms from these sources plus our own fact checks - not the other way around.
What other reviewers say
Heads-up: most crypto card "reviews" are affiliate content. We mark our reliability judgement on every source and include critical voices deliberately.
No third-party reviews with usable evidence found yet. In this niche that is itself a signal - most "review" sites are affiliate placements.
What users say (6)
Reddit, forums, complaint boards. Anecdotes, not proof - but patterns across threads are the best early-warning system this industry has.
Brand-sub announcement post: EUR deposits via SEPA at 0% fee with no FX markup (received via user email), plus a $50 cashback campaign (min $2,000 SEPA deposit + $1,000 card spend). Documents live EEA banking rails.
Hands-on availability test with an Indian profile: 'KAST no longer publishes a country list anywhere, so it's out until an actual Indian holder says otherwise.' Notes a transparency regression - the 170+ countries claim is no longer backed by a public country list.
Egyptian user report (Arabic): ordering the physical KAST card triggered a DHL customs-clearance invoice >2,000 EGP; KAST support refunded the charge. Real-world data point on physical-card shipping to MENA.
A user tested eight crypto cards including Kast with small real purchases in South Africa, measuring effective FX costs, fees and cashback. Kast scored well for large USD/Solana spends but was rated poor for small local purchases due to flat fees.
A user raises concerns that KAST treats stablecoin deposits as a sale, meaning users hold a USD balance on KAST's internal ledger rather than the original stablecoins.
A user asks for truly self-custodial crypto cards and reports that both KAST and RedotPay froze their accounts over two years, with about $5,000 in frozen funds and difficult support experiences.
Who is behind KAST?
Card programs stand and fall with their operator and BIN sponsor. This is what we could verify - with sources. Confidence: high (checked 2026-09-18).
Operator
KAST
Legal entity / issuer
KAST Tech as KAST - financial technology company; banking-like services (virtual accounts, cards, custody, on/off-ramp) provided by licensed partners
Registered in
Singapore (app store) / global operations
KAST Tech as KAST. The KAST Card IS a credit card: "The KAST Card, issued as part of the Card Issuance Services, is a credit card" (T&C) - charge-style with 0% APR and 21-day payment terms, spending backed by a custodial stablecoin balance (collateral clauses). Issuer: Third National (Nimbus LLC dba Third National, Visa issuer, Puerto Rico money transmitter NMLS #2612780). Verified 2026-10-03.
Every external source used on this page, with the date we fetched it. Methodology: how we verify. Sources disappear or change - if a link is dead, tell us via contact. Quoted text is the verbatim excerpt this review cites.
“Cashback is earned on eligible card purchases only, up to each tier's monthly spend cap; some merchant categories are excluded. KAST Points are not cash and have no guaranteed monetary value.”
“The KAST Card, issued as part of the Card Issuance Services, is a credit card that can be used at retailers, merchants, online website accepting cards from the relevant Card Network.”
The mainstream choice if you want crypto spend inside a full banking app - regulated, mature, multi-plan. Crypto card payments carry no exchange fee but the plan fair-usage limit counts crypto exchanges, each payment is a taxable disposal, and the September 2026 data breach exposed identity and transaction data. Solid for banking, honest about the crypto side-feature trade-offs.
Vivid's consumer crypto card is alive and regulated: free-first physical Visa, 300+ coins from EUR 1 under a Dutch AFM MiCAR CASP licence (custody via Copper), 2% default crypto trading fee and plan-capped cashback. The B2B pivot is real but the personal product demonstrably operates - with a documented 2026 freeze/support complaint pattern typical of partner-rail neobanks.
The strongest mainstream exchange debit card for UK/EEA/US users on paper: free issuance, no monthly fee, 0% FX on the Mastercard rate, instant tiered cashback up to 2% and a metal card for high-balance users. The catch: cashback only starts above a GBP/EUR 200 average balance, crypto spend carries an undisclosed spread, and per-day limits are not published.
Full KYC2% backphysical card0% FX
0% load · 0% FX · 2% back in cash (GBP/EUR) or BTC

No comments yet - be the first. No account needed; the anti-spam proof runs in your browser.