The most complete self-custodial spending stack in this comparison: your own vault plus real bank rails in four currencies (ACH, SEPA, GBP FPS, Swiss IBAN), 3% ETHFI cashback on the first $2,000/mo with Category and 5% travel boosts, KYC light in practice (ID + liveness; proof of address only on request - verified first-hand September 2026 with a Paraguayan cedula and a German passport) and an uncapped public affiliate program. The documented risks are real: interest from the first tap in Borrow Mode, liquidation risk, the November 2025 fraudulent-card incident with promised refunds, a protection program still marked not yet live that excludes compromised keys, and cashback now locked in volatile ETHFI instead of instant USDC.
site reachable (bot-protected) · checked 9 h ago · daily check
Review
by the cryptodebitcards editorial desk · curated review · prose updated 2026-11-04 · facts as of 2026-11-04 · how we verify
Overview
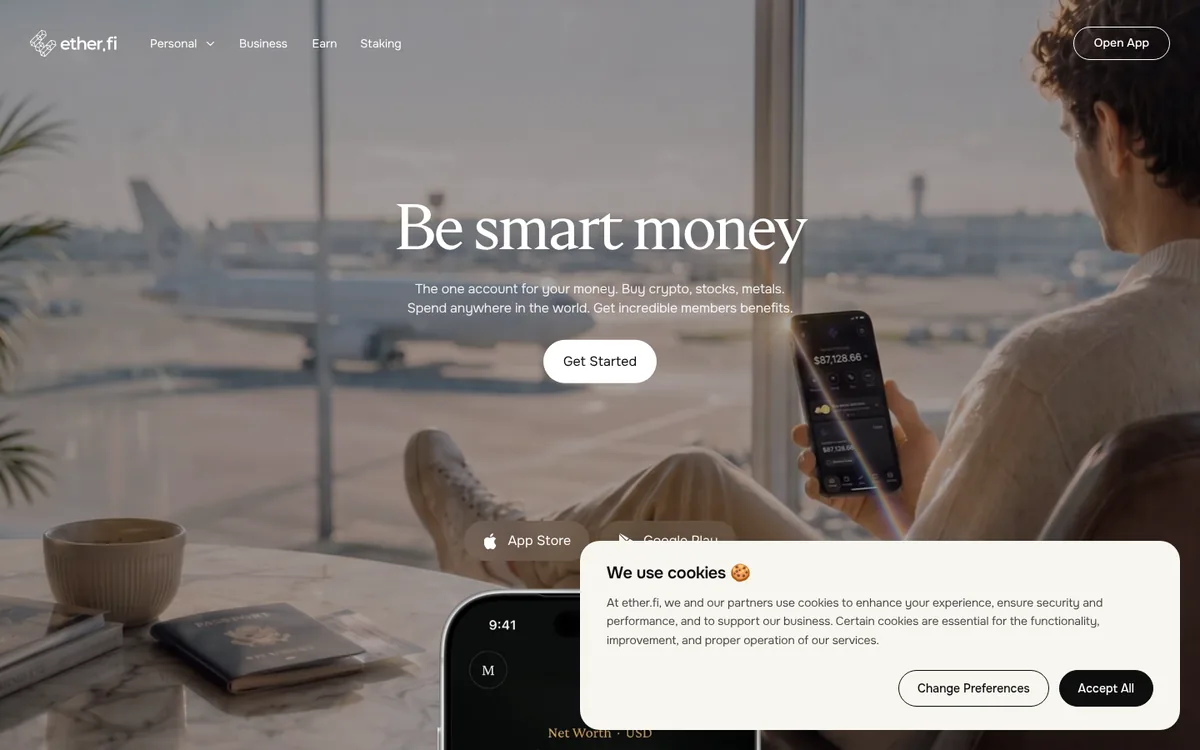
ether.fi Cash homepage - live capture 2026-09-19
ether.fi Cash is the self-custodial Visa card of the ether.fi DeFi protocol: your assets stay in a vault you control, and the card spends either directly from that vault (Direct Pay, USDC first, then LiquidUSD) or through a credit line against the portfolio (Borrow Mode via Aave v4 markets) [20][22]. The card is issued by Third National under a Visa licence, with the Rain infrastructure running settlement [20][27]. The program has scale: more than 75,000 active cards as of March 2026 and $109.5M of tracked card spend in August 2026 [27]. What makes it unusual in this comparison is self-custody plus a full banking layer (USD, EUR, GBP, Swiss franc accounts), a 3% cashback ladder and a public affiliate program [4][10][14].
First-hand test (editorial)
In September 2026 we opened two personal accounts with residence in Costa Rica: one verified with a Paraguayan cedula, one with a German passport [1]. Both went through the standard flow of phone code, ID photo and liveness selfie; no proof of address was requested, and neither account was asked for the $10 pre-verification deposit that the help center now documents [1][2]. Both verifications cleared within the hour [1]. The cards have not yet been used for everyday spending - this test covers onboarding only.
Fees & Costs
Item
Cost
Core virtual card
Free (except $10 first-card fee in 12 regional-pricing countries) [12]
Core physical card
$50, shipping fee applies, address immutable after ordering [12][25]
Core/Luxe free up to 10 per month, Pinnacle/VIP free unlimited [12][17]
The FX margin rides on an unpublished base rate; third parties put it near 1% outside USD and EUR [18][26]. A measured EUR purchase settled 0.015% below the ECB reference rate, so the 0% EUR promise is real [24]. ATM cash costs no operator fee at the free allowances, but third-party reviews report 2% plus a $250 daily cap that appears on no official page - treat as unconfirmed [26]. The expensive lever is Borrow Mode: interest starts with the first payment and never pauses, and stablecoins borrow at up to 90% LTV against a 95% liquidation threshold [22].
Banking: IBAN, ACH and local rails
The Cash account is one of the few crypto cards in this comparison that behaves like a bank account, not just a prepaid wallet: deposits arrive into the vault as stablecoins, withdrawals go out to any bank account [4].
Beyond those four currencies, deposits run over PIX (Brazil), SPEI (Mexico), BREB (Colombia), Interac (Canada) and more, with Cash App, Apple Pay and Stripe debit card deposits reserved for US users; payouts additionally cover UPI in India and local transfers in several markets [5]. Third-party deposits and withdrawals are supported, microdeposits work for account verification, and the app generates account statements plus a proof-of-ownership letter that includes your IBAN [4]. Members can also pay each other free of charge through a personal @name Tag [32]. The catch: card eligibility is a closed country list - if your jurisdiction is not listed, you cannot apply, and Belgium and Ireland get no physical card [3]. Bank transfers are additionally unavailable to residents of Indonesia, Malaysia and Thailand, except VIP members [9].
KYC & Onboarding
Verification gates the card and fiat rails, not crypto deposits [1]. The flow is a phone OTP, a photo of a passport, national ID card or driver's license, a liveness selfie, your residential address and, in some cases, a proof-of-address document (utility bill, bank or credit card statement, under 3 months old) [1]. Most verifications are reviewed within 48 hours [1]. Since late 2026 a $10 deposit is required before card verification completes, refundable if you walk away [2]; a first-hand reviewer describes this reversed order as a trust test [28]. Residence country, address document and IP location must match, and VPN use during sign-up is prohibited [33].
Coins & Top-up
There is no classic top-up step: the vault itself is the balance [22]. Crypto deposits (ETH, BTC, USDC, USDT and more, on 14+ networks including Ethereum, Optimism, Base, Arbitrum, Solana and Tron) need no verification; USDC and USDT addresses are network-specific, and a wrong-network send is the classic unrecoverable mistake [22][25]. The card rails moved from Scroll to Optimism in 2026, carrying $220M of TVL in three days [25]. In Direct Pay the card consumes USDC first, then the LiquidUSD yield vault; Borrow Mode draws credit against the portfolio instead [22]. EUR deposits arrive as EURC, Swiss francs as ZCHF [7][8].
Rewards
Cashback is paid in ETHFI: authorized purchases accrue pending cashback in dollar terms, conversion happens at clearing, and the tokens enter a 7-day lock before you can claim from $5 accrued [10]. That is a real change: into September 2026 the payout was instant USDC, which a measured test confirmed ($0.15 back on a $5.00 charge); the ETHFI switch with the lock came after [24]. The ladder, applied progressively across one shared monthly USD/EUR counter [10][12]:
Level
USD band at top rate
EUR band at top rate
Core
3% on first $2,000, then 1% to $3,000, then 0.5% [10]
3% to $800 USD-equivalent, 1% to $1,500, then 0.1% [10][29]
Cashback+ stacks Category Cashback for subscriptions (Luxe 10% up to $10 per month, Pinnacle 20%/$20, VIP 30%/$30, over named brands from ChatGPT to Netflix, switchable every 30 days) [11], ether.fi Travel pays 5% plus up to 65% off hotels and flights at every level [12], and tax and rent payments earn cashback since late October 2026 [10]. Excluded: ATM withdrawals, cash advances, P2P transfers, gift cards and gambling merchant categories; refunds reverse the cashback [10]. Third-party reporting adds weekly per-card MCC ceilings from $500 (crypto, gambling) to $30,000 (advertising) that appear in-app rather than in the help center [26].
Referral & Affiliate Program
The legacy referral program (1% of a referral's spending for 12 months) was closed and replaced by an affiliate program open to all users [14]. A referral counts once the new user signs up via your link, activates the card and spends $100 of eligible card spend [14]. Rewards scale across four tiers tied to qualifying-referral counts (Tier 2 from 50 all-time and 10 in the last 90 days) [14]:
Second-degree revshare of 20% unlocks at Tier 2, rewards have no caps and run for as long as referrals keep spending, and payment lands in USDC in your vault on the 15th of the following month [14][15]. Referred users can enter through referral campaigns that boost their cashback for specific categories, such as food and dining, under campaign-specific terms [16]. Two caveats: ether.fi clawed back referral rewards from at least one user it accused of fraudulent referral activity [26], and Reddit referrer posts for this card are dominated by referral-link spam, which we discard as astroturfing.
What users say
The picture is split, and both halves are documented. On the positive side: a long-term Austrian user reports EUR deposits auto-converting to EURC at zero fee and the EUR cashback ladder working as advertised [29]; a r/defi reviewer highlights dual verification through Sumsub and Persona, effectively no spending caps and weekend support answers within 10 minutes [30]; a Trustpilot reviewer praises support that answered in about 15 minutes [26]; a hands-on tester had a virtual card issued free within moments of KYC approval [25].
The negative half matters more. A r/etherfi user reports promotional cashback from a 10% Christmas campaign never arriving, with the account side zeroed out as well [31]. A Trustpilot roundup around 3.3 out of 5 across 47 reviews describes KYC limbo lasting weeks, unexplained fraud accusations and a SEPA deposit of EUR 1,000 stuck for weeks [26]. An operator-freeze test ended well: a suspension on unfounded cashback-farming suspicion was reversed in under 24 hours, with on-chain withdrawals open throughout - self-custody proved itself where custodial cards fail [24]. Alcohol and tobacco merchants declined repeatedly across countries [24].
Reliability & Red Flags
The documented incident: in November 2025, users reported fraudulent charges on never-used cards; ether.fi suspended affected cards, the CEO promised refunds for all affected users and stated the company does not access bank card data or user PII [23]. The issuer is nameable: Third National, the trading name of Nimbus LLC, a Puerto Rico money transmitter (NMLS 2612780) in the Rain group, issuing under a Visa licence - a money transmitter licence, not a bank charter, with no deposit insurance [20][27]. Disputes must be reported within 60 days of the statement [27].
The protection program is the weakest documented promise: the help center still lists it as not yet live, the caps ($10,000 Core to $500,000 VIP against $5 million total capacity) exclude the most likely loss path - compromised keys, credentials and devices - a $100 claim fee applies, and one official page states a different Pinnacle cap ($100K) than the program article ($200,000) [19][12]. Add the Borrow Mode interest and refund traps [22], ETHFI volatility with a 7-day lock [10], and the operator's right to cap monthly rewards [26].
Verdict
For DeFi users holding stablecoins or ETH, this is the most complete self-custodial spending stack we track: your own vault, real bank rails in four currencies, a 3% headline cashback with documented mechanics and an onboarding that accepted a Paraguayan cedula and a German passport without an address document [4][10][1]. Treat it as a spending account with sharp edges, not a bank: keep Borrow Mode off until you have read the liquidation math [22], claim cashback after the lock and sell if you do not want ETHFI exposure [10], and keep balances you could afford to have frozen during a compliance review - self-custody kept withdrawals open when it mattered, but the card and banking rails sit with a non-bank issuer whose most recent public incident is the November 2025 fraud wave [24][23][27]. If you need e-money safeguards, this is not that product - the operator says so itself [20][27].
What works
Fully non-custodial - assets stay in your own vault, card suspensions did not block on-chain withdrawals
Real banking rails: personal USD account (ACH/Fedwire), EUR IBAN (SEPA incl. Instant), GBP FPS, Swiss IBAN via Mt Pelerin, third-party transfers supported
3% ETHFI cashback on the first $2,000/mo (Core), Category Cashback and 5% travel cashback
KYC light in practice: passport, national ID (e.g. Paraguayan cedula) or driver's license + selfie; proof of address only on request - verified first-hand September 2026
0% FX on EUR merchants (measured at the ECB reference rate), no monthly or top-up fee
High limits: $5,000 per ATM withdrawal, $25,000/24h, user-settable card limits
Public uncapped affiliate program: $10-25 bonuses, 0.1-0.3% of referral spend, 50% card-fee commission
What to watch
Borrow Mode: interest from the first tap, no grace period, liquidation risk on volatile collateral
Cashback in ETHFI with 7-day lock and $5 claim minimum - instant-USDC era ended September 2026
November 2025 fraudulent-card incident with card suspensions (refunds promised)
No physical card for Belgium/Ireland; Netherlands, Finland, Estonia and others not eligible at all
Account protection program still "not yet live" and excludes compromised keys/devices
EUR cashback ladder much tighter than USD (3% only to $800 USD-equivalent, then 0.1%)
Accounts can be suspended on suspected cashback-farming or "fraudulent referral activity" - card and bank rails stop, while on-chain withdrawals stay open
Age-restricted merchants (alcohol, tobacco) declined repeatedly across countries (first-hand third-party report)
Cashback terms let ether.fi cap monthly rewards at its discretion
Fee reality check
Issuance
Core: one free virtual card (a $10 first-virtual-card fee applies in AR, AO, BD, BO, CO, EC, ID, MY, MX, NG, PE, PH, ZA, TH); physical card $50 for Core (help-center physical-cards FAQ table lists $10 virtual / $100 physical for Luxe and Pinnacle; VIP row cut off in static render).
Monthly
none
Top-up fee
0%
FX fee
1%
ATM fee
ATM withdrawals possible worldwide (except North Korea, Iran, Myanmar): Core/Luxe free up to 10 withdrawals per month, Pinnacle/VIP free unlimited (benefits table); no operator ATM % published ("standard ATM and network fees may apply"). Third-party sites report 2% plus a $250 daily cap - not confirmed by any official page.
Fine print
FX: prevailing base rate (third parties report ~1% outside USD/EUR) plus tier margin - Core 0.5%, Luxe 0.25%, Pinnacle/VIP none; EUR-merchant purchases 0% markup (measured 0.015% below ECB reference by sweepbase, 2026-08-04). Card costs: Core virtual free (except $10 first-card fee in 12 regional-pricing countries: AR, BD, BO, CO, EC, MY, MX, NG, PE, PH, ZA, TH), Core physical $50; Luxe/Pinnacle metal $100 after 1/2 free cards; VIP free. Membership: Luxe $199/yr or 5K points or $15K Liquid or 30K staked ETHFI; Pinnacle $999/yr or 25K points or $100K Liquid or 150K ETHFI. Borrow Mode interest starts immediately (Aave v4 variable APY).
Three steps, based on the operator-documented facts in this review (fact status: verified 2026-11-04):
Sign up. a light identity check (ID photo or similar) is documented before first use.
Top up. Native top-up coins: ETH, BTC, USDC, USDT, EURC, LiquidUSD, ZCHF. Load fees are in the fee table above.
Spend or withdraw. virtual and (where issued) physical card payments. ATM withdrawals are documented - check the ATM fee rows above before relying on cash.
Check your country. Documented region: USA, UK, Europe (EEA), APAC, LATAM, MENA. Run the region checker for exclusions named by the operator.
Open to all users. Qualifying referral = signup via link + card activation + $100 eligible spend. Four tiers (T2: 50+ all-time & 10+ in 90d; T3: 100+/20+; T4: 500+/50+). Rewards: new-member bonus $10-20, high-spender bonus $15-25, 0.1-0.3% cashback on referral spending, 20-25% physical-card commission, 50% card-fee commission, 5-12.5% liquid/staked yield revshare, 20% second-degree revshare from Tier 2. No caps, lifetime; paid in USDC to the vault on the 15th of the following month. Referral campaigns add boosted cashback for referred users (e.g. 15% on dining). Legacy 1%-for-12-months program closed to new participants (help.ether.fi articles 662040/304984, ether.fi/affiliates, checked 2026-11-04).
Based on our checks as of 2026-11-04: ether.fi Cash scores 7.6/10 in our weighted review. We logged no red flags. User reports and the operator background are documented with dated sources in the meta-review below.
The meta-review: what the internet says about ether.fi Cash
We do not expect you to trust us. This review is a meta-review: below you see what other review sites claim, what users report on Reddit and forums, and who actually operates ether.fi Cash - including the issuing structure behind the card. Every claim links to its source so you can verify it yourself. Our verdict forms from these sources plus our own fact checks - not the other way around.
What other reviewers say (5)
Heads-up: most crypto card "reviews" are affiliate content. We mark our reliability judgement on every source and include critical voices deliberately.
Review documents the four-tier membership (Core free, Luxe, Pinnacle, VIP): Core 3% cashback on the first $2,000/month, 0.5% FX fee, free annual fee, physical card with shipping charged; published cashback up to 4% at VIP, converted to ETHFI after each purchase clears; defining feature is borrowing against staked ETH (eETH/weETH) instead of selling.
Ether.fi paid $0.15 on a $5.00 charge, which is 3% to the cent ... it arrived as USDC under the rules then in force. Since 12 September 2026 the payout has been ETHFI. ... In May, Ether.fi suspended my card services on suspicion of cashback farming ... Support reviewed it and restored the account in under 24 hours ... Withdrawals stayed open on-chain the entire time.
On 3 September 2026 we opened an account, and the virtual card was issued. ... KYC usually 5 to 30 minutes. ... Standard shipping runs 15 business days or more, and the address cannot be changed after ordering. ... 70,000 active cards across 300,000 accounts. Moving Cash to Optimism in 2026 shifted $220M of TVL in three days with no downtime.
Trustpilot sits around 3.3 out of 5 across 47 reviews ... First, KYC limbo - weeks to months stuck in address verification. ... Weekly per-card limits by merchant category run $500 for crypto purchases, gambling, FX and prepaid loading ... $3,000 for pharmacies ... $30,000 per transaction for advertising.
I had to deposit $10 in crypto before I could begin KYC for the card. ... After the deposit, KYC was easy in my experience. The flow was guided, the requests made sense, and I did not have to repeat uploads.
What users say (5)
Reddit, forums, complaint boards. Anecdotes, not proof - but patterns across threads are the best early-warning system this industry has.
A user documents a detailed two-card setup for EU residents combining the COCA card with the ether.fi Cash card, including ether.fi's 3% EUR cashback tiers, USDC payouts and 3.5-5.5% Earn vault yield.
Card Verification (via Sumsub) ... Account Verification (via Persona). ... There are no spending limits. If you have the balance, you can literally run a million-dollar transaction through the card. ... I contacted them on a weekend and got a clear, helpful response within 10 minutes.
I participated in the 10% cashback Christmas promotion. I used the card, reaching the maximum limit of $40, and the money never reached my account. ... When asked for the reason, they insist it violated the rules, but they don't specify why.
A user says they stopped recommending ether.fi because the 3% stablecoin cashback was changed to earn in the platform's own token, and asks for alternatives paying in BTC or USDC.
Who is behind ether.fi Cash?
Card programs stand and fall with their operator and BIN sponsor. This is what we could verify - with sources. Confidence: high (checked 2026-09-18).
Operator
ether.fi
Legal entity / issuer
ether.fi (Ethereal Foundation / Ether.fi Labs); card issued subject to separate terms by a third-party Issuer
Registered in
Global (Cayman/BVI-anchored protocol entities typical)
Established liquid-restaking protocol (eigenlayer-era leader, live since 2023) with governance forum/snapshot voting; Cash card is an app-level product not affiliated with the protocol. App on iOS/Android.
Every external source used on this page, with the date we fetched it. Methodology: how we verify. Sources disappear or change - if a link is dead, tell us via contact. Quoted text is the verbatim excerpt this review cites.
“Upload a clear photo of a valid, government issued ID. Accepted documents - Passport, National ID card, Driver's license. In some cases, you may be required to submit proof of address. Most identity verifications, including Cash card verification and bank transfer verification, are reviewed within 48 hours.”
“A $10 deposit is required before card verification can be completed. ... If your verification is unsuccessful or you decide not to proceed with verification, you can withdraw the funds you deposited at any time.”
“Physical-card delivery is not available in every eligible Cash region. ... Belgium and Ireland are eligible regions for ether.fi Cash. However, physical Cash card delivery is not currently available in these regions. ... If your jurisdiction is not listed, you will not be able to apply for a Cash card at this time.”
“USD ACH $0.50 + 0.10%. USD domestic wire $20.00 + 0.10%. EUR SEPA to USDC EUR 0.90 + 0.15%. EUR SEPA to EURC EUR 0.90. GBP Faster Payments GBP 0.90 + 0.20% FX. CHF bank transfer No fee. ... Third party payments are supported.”
“ACH funding - 1-2 business days (please allow up to 3-4 business days for provider and bank processing). Fedwire funding - typically same day. ... Funding ACH - $0.50 + 0.10%. Outgoing ACH - $0.50 + 0.20%.”
“SEPA Instant deposits - accepted where your sending bank supports SEPA Instant; transfers commonly arrive instantly or the same day. Standard EUR SEPA deposits - 1-2 business days. ... Issuing institution - ClearBank Europe N.V., Amsterdam.”
“You can get a personal Swiss IBAN in your ether.fi account. CHF you send to it arrives in your Vault as ZCHF, a Swiss franc stablecoin. ... CHF bank transfers are provided by Mt Pelerin, an independent Swiss company. ... There is currently no fee for CHF transfers.”
“Earn ETHFI cashback on qualifying Cash card purchases, eligible trades and eligible USD/EUR borrowing. ... Once the purchase clears, your cashback is converted to ETHFI at the current price and enters a 7-day lock period. ... USD - First $2,000 - 3%. ... As of October 30, 2026, Tax Payments (MCC 9311) and Rent Payments processed under MCC 6513 earn cashback at your normal rate.”
“Luxe - Earn 10% Category Cashback, up to $10 per month. Pinnacle - Earn 20% Category Cashback, up to $20 per month. VIP - Earn 30% Category Cashback, up to $30 per month. ... You can select and change your category every 30 days.”
“You can buy Luxe ($199/year) or Pinnacle ($999/year) and get that level's benefits right away for 12 months. ... To level to Luxe, you need 5K points to activate and 5K points/mo to maintain. ... Cash 1,000 points per $1k spend.”
“A referral becomes a conversion once they have completed at least $100 USD in eligible spending using their ether.fi Card. ... New member bonus $10 / $15 / $20 / $20. Cashback on referral spending 0.1% / 0.2% / 0.25% / 0.3%. Card fee commission 50%. ... Rewards are paid in USDC directly into your Vault with Cash.”
“Lifetime rewards. No caps, earn for as long as your referrals keep spending with ether.fi Cash. ... Physical card commission 20% / 20% / 20% / 25%. ... 2nd degree revshare 20%.”
“Referral Campaigns are special promotions that allow eligible users to earn additional cashback when they join ether.fi through a participating referral campaign. ... The cashback rate and maximum reward depend on the specific campaign and your region.”
“Up to $5,000 per withdrawal. Up to 5 withdrawal attempts in a rolling 24-hour period. Up to $25,000 in a rolling 24-hour period. ... Every attempt counts, including declined ones.”
“Membership Level / Added FX fee - Core 0.5%. Luxe 0.25%. Pinnacle None. VIP None. ... ether.fi applies the prevailing FX base rate and may add a foreign exchange margin on top of that base rate.”
“The ether.fi Cash Protection Program is not yet live. ... Core $10,000, Luxe $50,000, Pinnacle $200,000, VIP $500,000. The Program will have a total capacity of $5 million. ... a $100 processing fee will apply. ... The Cash Protection Program isn't an insurance policy.”
“Interest starts immediately and never pauses. There is no grace period. ... a refund does not automatically repay or reduce what you owe in Borrow Mode.”
“In response to concerns circulating in the community that a card that has never been used for any transactions/pre-authorizations [was] fraudulently used and suspended, EtherFi CEO Mike Silagadze stated, We are investigating this matter and communicating with our credit card partners. All users who experienced fraudulent transactions will receive a refund.”
“Ether.fi paid $0.15 on a $5.00 charge, which is 3% to the cent ... it arrived as USDC under the rules then in force. Since 12 September 2026 the payout has been ETHFI. ... In May, Ether.fi suspended my card services on suspicion of cashback farming ... Support reviewed it and restored the account in under 24 hours ... Withdrawals stayed open on-chain the entire time.”
“On 3 September 2026 we opened an account, and the virtual card was issued. ... KYC usually 5 to 30 minutes. ... Standard shipping runs 15 business days or more, and the address cannot be changed after ordering. ... 70,000 active cards across 300,000 accounts. Moving Cash to Optimism in 2026 shifted $220M of TVL in three days with no downtime.”
“Trustpilot sits around 3.3 out of 5 across 47 reviews ... First, KYC limbo - weeks to months stuck in address verification. ... Weekly per-card limits by merchant category run $500 for crypto purchases, gambling, FX and prepaid loading ... $3,000 for pharmacies ... $30,000 per transaction for advertising.”
“Third National is the trading name of Nimbus LLC, a US money transmitter, NMLS 2612780 ... more than 75,000 active cards as of March 2026 (Rain) ... Card spend, August 2026 - $109.5M, tracked onchain by Paymentscan ... a disputed charge must be reported within 60 days of the statement.”
“I had to deposit $10 in crypto before I could begin KYC for the card. ... After the deposit, KYC was easy in my experience. The flow was guided, the requests made sense, and I did not have to repeat uploads.”
“You deposit Euro via bank transfer, and the app instantly and automatically converts it into EURC with zero conversion fees. ... the base tier gives you 3% cashback on your first 800 euro of spending, dropping to 1% on the next 700, and tapering to 0.1% after that.”
“Card Verification (via Sumsub) ... Account Verification (via Persona). ... There are no spending limits. If you have the balance, you can literally run a million-dollar transaction through the card. ... I contacted them on a weekend and got a clear, helpful response within 10 minutes.”
“I participated in the 10% cashback Christmas promotion. I used the card, reaching the maximum limit of $40, and the money never reached my account. ... When asked for the reason, they insist it violated the rules, but they don't specify why.”
“Your Tag is your name on ether.fi. When someone pays your Tag, the money goes to your ether.fi account. It's free to claim. ... Tag length minimum depends on membership level - VIP 3, Pinnacle 4, Luxe 5, Core 6 characters.”
“The residence country you declare, your proof of address country, and the country identified from your internet connection (IP address) must match. You should not use a VPN during sign-up or verification.”
Bleap is one of the few crypto cards whose core fee promises check out: free issuance, no monthly fee, Mastercard rate with no FX markup, and free ATM withdrawals up to 400 EUR/month, all debited from a genuinely non-custodial MPC wallet with a named Cypriot EMI issuer and a verifiable MiCA CASP license. The catch is that the famous 'up to 20% cashback' is a lattice of category promos with small eligible-spend caps (realistic value is roughly 1% on everyday spend up to 3,000 EUR/month), the 2% groceries and dining rate already expired in May 2026, rates can change without notice, and the physical card is referral-only. Availability is EEA plus Switzerland only, with 45 excluded nationalities and some EEA countries still on a waiting list.
Watch for the December 2026 sunset: the consumer product is closing. Solid self-custody architecture (card only moves whitelisted tokens from your Safe to settlement, up to a daily limit), but as a spending card it has an end date. Migrate to a partner app (Rebind/Picnic) or another self-custody card before 20 December 2026.
Full KYCphysical cardself-custody0% FXclosing 2026-12-20
The most mainstream self-custody card: MetaMask wallet spending stablecoins on Linea through a Mastercard program run with Baanx/Monavate, keys stay yours. 1% mUSD cashback on the orderable Virtual card; US and UK sign-ups are paused, Metal (3% tier) paused since June 2026. Verify current availability in-app before ordering.


No comments yet - be the first. No account needed; the anti-spam proof runs in your browser.