A non-custodial stablecoin wallet with a Wirex-issued prepaid card: documented 1-8% cashback tiers in stablecoins, free virtual card, Apple Pay/Google Pay and up to 5% APY. The rewards are real but tiered behind $COCA balances, the official pages contradict each other on cashback rate and card network, and the independent FX spread measurement undercuts the 0% FX marketing. Verify the current card terms in-app before loading.
Full KYC8% backphysical card0% FX5 red flagsfacts reported
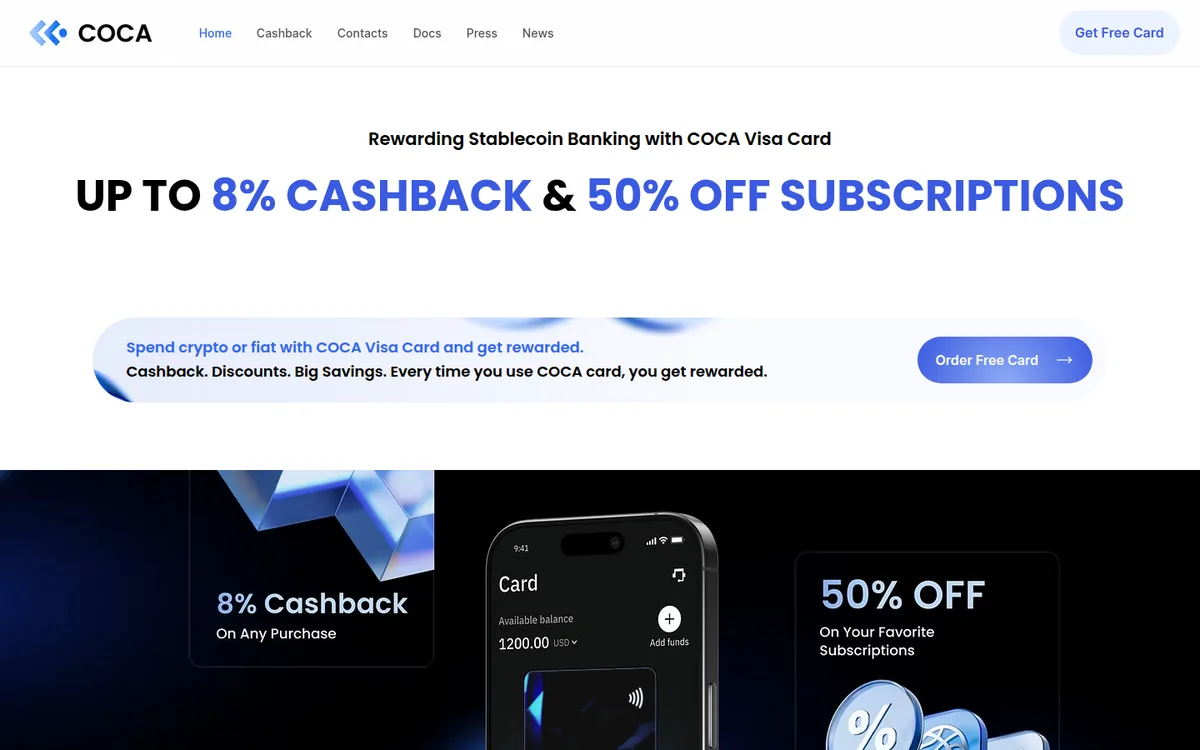
Official messaging is internally inconsistent: homepage headline says 8% cashback, the same page's meta description says 5% (checked 2026-10-01)
Card network contradiction: homepage says Visa, the /cards page says Mastercard issued by Wirex
Top cashback tier (8%) requires 30,000 $COCA; tier activation described as balance-based on the marketing page but staked with 30-day cooldown in the docs
+2 more red flags - expand before loading funds
Official '0% FX' claim contradicted by an independent 1.18% measured FX spread
Support's no-CRS/DAC8-reporting claim unproven
Review
by the cryptodebitcards editorial desk · curated review · prose updated 2026-10-01 · facts as of 2026-10-01 · how we verify
Overview
COCA homepage - live capture 2026-09-19
COCA is a non-custodial stablecoin wallet with a prepaid card attached: the wallet is a smart wallet you control per the operator terms [5], and the card side is issued in partnership with Wirex - the cards page names a prepaid Mastercard issued by Wirex Limited in the UK or UAB Wirex in the EEA [6]. The reward headline is cashback of up to 8% in stablecoins plus 50% rebates on subscriptions [1][2]. The structure matters for your risk picture: your stablecoins sit in your own wallet, but the card is a Wirex prepaid e-money product, so the spending side is custodial in exactly the way the wallet is not [5][6].
Fees & Costs
The documented fees are light: no monthly fee, a free virtual card, and the physical card at a one-time fee on the lower tiers [6]. ATM withdrawals are fee-free up to the documented monthly allowance and cost 2% beyond it [6]. The operator markets 0% FX, but the only measured evidence we have found documents a spread of about 1.18% on converted spending - a third-party measurement, not the operator [8]. Funding runs through stablecoin transfers to your own wallet, SEPA and card loads on the account side; no load fee is stated in the banking-account docs [6]. We do not treat the 0% FX marketing as verified [5].
KYC & Onboarding
The card program requires full KYC, because the issuer is a regulated e-money institution [6]. The wallet marketing advertises no KYC hassles for the wallet itself, but the two claims live on different layers: the non-custodial wallet is your software, the card is Wirex-issued e-money with its own onboarding [5][6]. Onboarding runs through the COCA app, and the card attaches after the issuer's verification completes [6].
Coins & Top-up
You fund the wallet with stablecoins - USDT and USDC are the documented loads [5]. The wallet is non-custodial, so the balances stay under your control until each payment authorizes them [5]. There is no documented direct crypto top-up beyond stablecoins and no Lightning support. The card spends against the wallet balance, and the operator describes the authorization flow as per-payment rather than a pre-loaded card balance [5][6].
Rewards
The cashback ladder is documented in the official docs: the base tier earns 1% unlimited with no $COCA balance required, and each higher tier raises the rate and the monthly limit - 3% on the first 1,000 dollars per month at Standard, up to the Elite tier at 8% on the first 10,000 dollars per month, then 1% unlimited on all tiers [3][4]. Cashback is paid in stablecoins and settles monthly [2]. A user report confirms the mechanics from the receiving end: 3% on the first 1,000 dollars of monthly spending, then a flat 1% with no cap, paid monthly in USDC [8]. Two mechanisms are documented differently by the operator itself: the marketing page says tiers activate from your $COCA balance tied to usage, not staking, while the docs table still lists the tier amounts as staked with a 30-day cooldown [3][4]. The subscription rebate is a separate documented benefit at 50% on eligible services [2].
Reliability & Red Flags
The operator entity behind the wallet is CCA Labs, registered in Dubai [5]. The card issuer side is Wirex - named on the cards page [6] and corroborated by independent reviews [7]. Three inconsistencies sit in the official messaging itself, and we flag them rather than pick a side: the homepage headline says 8% cashback while the same page's meta description says 5% [1], the homepage and cashback page call the card a Visa card while the cards page and an independent review call it a Mastercard [2][6][7], and the tier activation mechanism differs between marketing and docs [3][4]. The user community documents both payouts and friction - real cashback receipts exist [8]. Our fact set is not fully verified (reported) as of the facts date; the Wirex issuer link is the most load-bearing unverified-at-issuer-level part, so a small test load is advised.
Verdict
Reasonable for stablecoin spending in Europe, Asia and other supported regions if you want wallet control plus a real rewards program [2][5]. Do not count on the 8% headline unless you hold a 30,000 $COCA balance [3][4], verify the card network and current terms in-app before ordering because the official pages contradict each other [1][6], and treat the 0% FX claim as marketing rather than a measured fact [5].
What works
Non-custodial wallet layer documented in operator terms and docs
Documented 1-8% cashback tiers paid in stablecoins, monthly settlement
Free virtual card, Apple Pay and Google Pay, free EUR IBAN
Multiple independent positive long-term user reports with cashback payouts
What to watch
Elite 8% tier requires a 30,000 $COCA balance
Official pages contradict each other: 8% headline vs 5% meta description, Visa vs Mastercard
Independent measurement found a ~1.18% FX spread despite '0% FX' marketing
No US/Canada availability
Card side is Wirex-issued prepaid e-money, not the non-custodial wallet itself
Fee reality check
Issuance
Virtual card free (all tiers); physical $5 for Starter/Standard/Standard+, free from Premium up
Monthly
none
Top-up fee
0%
FX fee
0% (own markup)
ATM fee
2% $0 up to $250/month, 2% thereafter (official docs; the /cards marketing page says $200 fee-free)
Fine print
No monthly fee; membership tiers are $COCA-staking based (cancel anytime, 30-day cooldown). Official marketing claims 0% FX ('zero FX fees on direct pairs'), but an independent r/CryptoCurrency test (2026-07-20) measured a 1.18% gross FX spread. ATM free to $250/mo then 2%. No top-up/load fee documented - funding via SEPA IBAN, external card or stablecoins; 'Zero COCA Fees' on buy-crypto and swaps (operator side). Reward withdrawals throttled by $15-$350/month claim capacity (SpendNode).
Three steps, based on the operator-documented facts in this review (fact status: checked 2026-10-01):
Sign up. full identity verification is required at signup.
Top up. Native top-up coins: USDT, USDC. Load fees are in the fee table above.
Spend or withdraw. virtual and (where issued) physical card payments. ATM withdrawals are documented - check the ATM fee rows above before relying on cash.
Check your country. Documented region: worldwide. Run the region checker for exclusions named by the operator.
Based on our checks as of 2026-10-01: COCA scores 4.5/10 in our weighted review. The card runs on a regulated issuing structure (see the operator section). We logged 5 red flags (listed above). User reports and the operator background are documented with dated sources in the meta-review below.
The meta-review: what the internet says about COCA
We do not expect you to trust us. This review is a meta-review: below you see what other review sites claim, what users report on Reddit and forums, and who actually operates COCA - including the issuing structure behind the card. Every claim links to its source so you can verify it yourself. Our verdict forms from these sources plus our own fact checks - not the other way around.
What other reviewers say (3)
Heads-up: most crypto card "reviews" are affiliate content. We mark our reliability judgement on every source and include critical voices deliberately.
Hands-on FX test (score 28): COCA ranks 2 of 8. Measured gross FX spread 1.18%, base cashback 1% (USDC, paid monthly), non-custodial, free virtual card, ~8 min setup. 'Good perks, stablecoin CB up to $10,000/month'. Note: measured spread contradicts the official '0% FX' marketing.
Austrian user (score 15) runs COCA Standard tier (300 COCA ~ EUR 350): 3% cashback on first $1,000/mo then uncapped 1%, paid monthly in USDC, 50% Netflix rebate. Criticism: EUR balance earns 0% APY - high yield only on USD stablecoins.
User asked COCA support about regulation: they claim NOT to report under CRS/DAC8 because they 'only offer non-custodial products' - while offering a Visa card and an IBAN. User: 'Sounds a little like Scam.' Unresolved regulatory paradox, no fraud evidence. Same text cross-posted to r/CreditCards and r/CryptoMarkets (counted once).
Daily user (score 5): 'COCA. Product that I use till today... 15+ networks, no bridging. Cashback in USDC, ~5% APY. 0% FX fees. The physical card cost around $5. It has IBAN, so your salary can be deposited directly... discounts on subs (youtube, gpt, amazon) and hotel booking via coca app.'
User recovered the COCA wallet seed in Trust Wallet and saw 0 balances (POL and COCA tokens) - consistent with MPC/smart-wallet key management, not proof of lost funds, but it unsettled the user.
Play Store review corpus for the COCA app contained many Wirex wallet reviews - consistent with Wirex being the card issuer.
Who is behind COCA?
Card programs stand and fall with their operator and BIN sponsor. This is what we could verify - with sources. Confidence: medium (checked 2026-09-19).
Operator
COCA
Legal entity / issuer
COCA (cards issued by Wirex Limited, UK / UAB Wirex, EEA - licensed e-money institutions)
Registered in
Unknown
Self-custody smart-wallet app (Privy key infrastructure, EIP-7702); card program operated with Wirex as issuing e-money partner. Support claims no CRS/DAC8 reporting (unverified, Reddit-sourced). 2026-10-01 re-check: coca.xyz + terms + docs name no issuer, BIN sponsor or program manager (only CCA Labs FZCO, Dubai, for the wallet); the site claims "non-custodial" and "without any KYC" - unverified marketing until the issuer identity is republished on the live site (our earlier Wirex issuing-partner note is not confirmed by current public documents).
Every external source used on this page, with the date we fetched it. Methodology: how we verify. Sources disappear or change - if a link is dead, tell us via contact. Quoted text is the verbatim excerpt this review cites.
The SafePal Card is a wallet-native on-ramp/off-ramp more than a rewards card: a virtual Mastercard debit (no PIN, no physical, no ATM) spending tokenised Swiss-fintech deposits (EUR24/USD24/CHF24 on Arbitrum) inside the SafePal app, with the IBAN account and compliance handled entirely by Fiat24 (SR Saphirstein AG, FINMA fintech licence Art. 1b). Fee transparency is genuinely good (0% standard top-up under the current waiver, 1% non-USD FX, no account fees), and 42 countries get Mastercard issuance. But there is no cashback, KYC includes a GPS-at-home check, and the two structural risks are serious: client deposits are explicitly NOT covered by the Swiss deposit protection scheme, and the issuer has spent most of 2026 in a maintenance mode that per community reports paused deposits and FX swaps. STATUS=verify until Fiat24's maintenance mode ends and SafePal onboarding is confirmed live end-to-end.
A real, shipping product from a well-funded Solana ecosystem team (Solayer Labs), now branded Solayer Pay after launching as the Emerald Card in April 2025. Virtual + physical Visa-compatible cards, Apple/Google Pay, ATM access, USDC-funded. Weaknesses: fee stack ($20/yr + 1% top-up + $0.15/txn + FX), no standing cashback (points with future promised utility), heavy restrictions (17 US states, most of Western Europe, CA/AU/NZ/IN/KR excluded), issuer not published, and 'non-custodial' marketing that contradicts its own hot/cold wallet security description. Fees/limits transparency is actually good (dedicated docs) — more than most competitors publish.
Phantom Cash finally gives the biggest Solana wallet a spending rail: a free virtual Visa paid out of a CASH stablecoin balance with Apple/Google Pay and yield on idle balances. But it is a US-only (ex-NY), virtual-only product with a USD 2,000 standard daily cap, 1.75% card funding and no card cashback - a nice extension of the wallet, not yet a full card program.

No comments yet - be the first. No account needed; the anti-spam proof runs in your browser.