A documented, fully-priced stablecoin Visa program with named regulatory registrations - but unresolved mega-litigation changes the risk picture: Binance sued RedotPay and its founders for ~$472.8M in August 2026 over alleged user-asset diversion. Custodial balances, freeze powers, no named issuer. Treat as usable-but-contested; keep balances minimal and watch the litigation.
Binance lawsuit (~$472.8M, Hong Kong, Aug 2026) alleging diversion of ~470,000 users' assets - unresolved litigation against the operator and founders
Custodial balances with documented freeze powers: accounts can be restricted or frozen if compliance checks fail
No issuing bank/BIN sponsor disclosed
+3 more red flags - expand before loading funds
Cashback (Pro) paid in USDs - in-app credit only, never withdrawable
FX 1.20% on non-default currency; ATM 2-3%
Base rewards are in-app points, not cashable
Review
by the cryptodebitcards editorial desk · curated review · prose updated 2026-10-01 · facts as of 2026-10-01 · how we verify
Overview
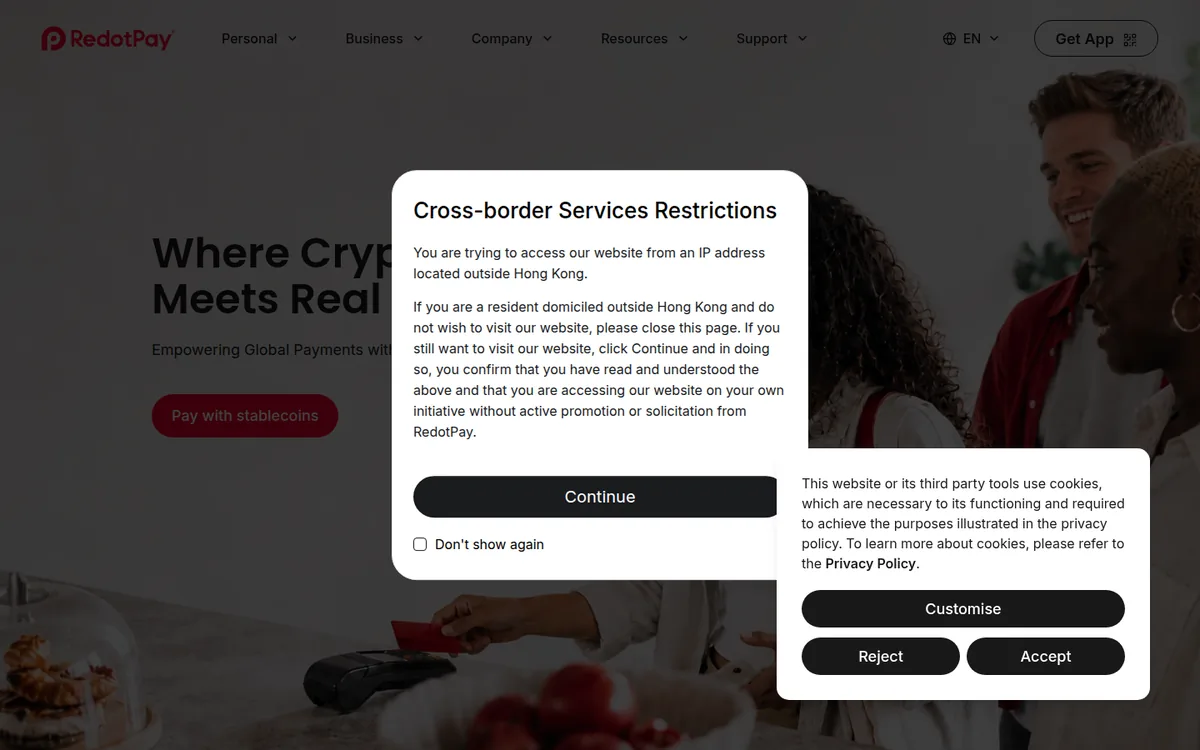
RedotPay homepage - live capture 2026-09-19
RedotPay runs a stablecoin-funded Visa card program out of Hong Kong, with a documented regulatory footprint (Argentina VASP authorisation, Canadian and FinCEN MSB registrations, per independent reviews) and a fee table the operator publishes in full [7][8]. The program served 8 million-plus users per its own marketing, and press reported IPO preparation with completed audits in September 2026 [7]. The dominant fact about this card is not the fees - it is the litigation: in August 2026, Binance sued RedotPay and its founders in Hong Kong for approximately 472.8 million dollars, alleging the diversion of about 470,000 users' assets [5]. The suit is contested, and RedotPay disputes the claims [5]. Everything else in this review should be read with that in the background.
Fees & Costs
The fee stack is verified against the operator's official table (help-center article updated in July 2026, values effective December 2025) [1]. Card issuance costs 10 dollars for the virtual card and 100 dollars for the physical card, with standard mail free [1]. Every transaction carries a 1% crypto-conversion fee [1]. There are no monthly or annual account maintenance fees - waived effective 1 December 2025 [1]. Foreign-currency transactions outside your default currency cost 1.2% [1]. ATM withdrawals cost 2% below a monthly volume of 10,000 dollars and 3% above it, with daily limits of 23,000 HKD or 3,750 USD and monthly limits of 75,000 HKD or 50,000 USD [1]. The Pro membership (12.90 dollars per month) waives the virtual-card fee [4]. A selected-merchant fee of 1.5% appears in independent reviews but not in the official table we verified - recorded as third-party-only [8].
KYC & Onboarding
KYC is unconditional: identity checks are required before you can use RedotPay at all - personal details, an ID photo and a face scan [2]. This corrects the older framing that verification waited for higher tiers; the current official copy is explicit [2]. Citizens of a documented restriction list cannot complete verification [3]. Onboarding timing is not documented in the sources we checked.
Coins & Top-up
Deposits run in major cryptocurrencies - USDC, USDT, BTC, ETH, SOL, TRX, TON, XRP, BNB, SUI and more, each restricted to specific networks [3]. Balances are custodial: once deposited for card use, custody sits with RedotPay and its card partners, and the account can be restricted or frozen if compliance checks fail [7]. Spending converts at the documented 1% transaction fee; non-default-currency spending adds the 1.2% FX line [1]. There is no direct on-chain spending and no Lightning support [1].
Rewards
The base product pays points for in-app rewards only - points cannot be cashed out, transferred or traded [4]. The Pro membership adds 3% cashback on Apple Pay and Google Pay purchases, capped at 18 dollars per month [4]. The cashback is issued in USDs - in-app credit usable only for future card transactions, explicitly not withdrawable as cash and not usable to purchase cards [4]. That is a spending rebate, not withdrawable value; price it accordingly [4].
Reliability & Red Flags
The documented risk picture: the Binance lawsuit alleging diversion of about 470,000 users' assets, filed in Hong Kong in August 2026 with a parallel Singapore case, is unresolved [5]. RedotPay disputes the allegations, completed a Big Four financial audit and an AML/CFT review in September 2026, and press reports a potential IPO [6]. Custodial balances carry documented freeze powers [7]. The issuing bank behind the Visa BIN is not disclosed anywhere in the official material we checked [1]. The operator's own restrictions list and KYC gating are documented [2][3]. No security breach of the card program itself is documented. Our fact set is verified against official sources as of the facts date; the litigation status is the part that will move.
Verdict
A transparently-priced program with real regulatory registrations [1][8] - and an unresolved 472.8-million-dollar lawsuit against its operators [5]. If you use it, keep balances minimal, rely on instant conversion rather than parked funds [7], and do not count the Pro cashback as money until you spend it in-app [4]. We will follow the litigation; until it resolves, this is a usable-but-contested tool, not a savings place [5]. The fee and KYC facts above are verified against the live help center; the litigation outcome is outside anyone's control and the one part we cannot price.
What works
Broad APAC availability and global marketing
USDT/USDC top-ups documented
What to watch
Fee schedule not independently verified (site bot-blocked)
Full KYC (HK-based program)
Heavy affiliate marketing around it - claims deserve extra scrutiny
Official fee table (helpcenter article updated 2026-07-24, image OCR): crypto-conversion fee 1.00% per transaction; no monthly or annual account maintenance fees (waived effective 2025-12-01); FX: non-default-currency transactions 1.20%; virtual card 10 USD, physical 100 USD (standard mail free). Third-party (review-only, not in the official table): selected-merchant transaction fee 1.5% min $0.50 with up to 3 monthly waivers. Pro membership ($12.90/mo or $129/yr) waives the virtual card fee and adds 3% Apple/Google Pay cashback up to $18/month paid in USDs (non-withdrawable credit).
Three steps, based on the operator-documented facts in this review (fact status: verified 2026-10-01):
Sign up. full identity verification is required at signup.
Top up. Native top-up coins: USDC, USDT, BTC, ETH, SOL, TRX, TON, XRP, BNB, SUI, S. Load fees are in the fee table above.
Spend or withdraw. virtual and (where issued) physical card payments. ATM withdrawals are documented - check the ATM fee rows above before relying on cash.
Check your country. Documented region: APAC, worldwide. Run the region checker for exclusions named by the operator.
Based on our checks as of 2026-10-01: RedotPay scores 4.4/10 in our weighted review. We logged 6 red flags (listed above). User reports and the operator background are documented with dated sources in the meta-review below.
The meta-review: what the internet says about RedotPay
We do not expect you to trust us. This review is a meta-review: below you see what other review sites claim, what users report on Reddit and forums, and who actually operates RedotPay - including the issuing structure behind the card. Every claim links to its source so you can verify it yourself. Our verdict forms from these sources plus our own fact checks - not the other way around.
What other reviewers say (4)
Heads-up: most crypto card "reviews" are affiliate content. We mark our reliability judgement on every source and include critical voices deliberately.
'RedotPay was founded in 2023 and is headquartered in Hong Kong. It was co-founded by Jonathan Chan and Michael Gao.' Also confirms: Pro ($12.90/mo or $129/yr) adds 3% Apple Pay/Google Pay cashback capped $18/month; base card has no meaningful cashback.
In-depth 2026 review: card setup fee $10 virtual / $100 physical (mailing waived), transaction fee 1.00% (virtual), 1.5% min $0.50 on selected merchants with up to 3 waivers/month, card/PayPal top-ups 3% (min $1), credit interest 0.05%/day simple. KYC = ID photo + face scan, sometimes personal statement. Card can be frozen after repeated wrong PIN/CVV entries. Praises breadth (card+wallet+transfers+credit), criticizes fee stacking and regional restrictions.
Stablecoin spending card in 100+ countries: issuance $10 virtual / $100 physical (non-refundable, 10/100 USDT), $0 monthly/annual/dormancy, 1% conversion + 1.2% FX cross-currency, ATM 2% up to $10,000/month then 3%, $50 chargeback fee (60-day window, 3-6 months resolution), issuing bank undisclosed. Verdict: narrow but coherent - hold stablecoins outside the US, fund on-chain for free, spend at Visa merchants at $0/month with 1.2% FX.
under several recognised regulatory frameworks , including VASP authorisation in Argentina , MSB registration in Canada , a FinCEN-registered MSB status in the
What users say (3)
Reddit, forums, complaint boards. Anecdotes, not proof - but patterns across threads are the best early-warning system this industry has.
Card programs stand and fall with their operator and BIN sponsor. This is what we could verify - with sources. Confidence: unknown operator (checked 2026-09-18).
Operator
RedotPay
Legal entity / issuer
RedotPay (Hong Kong entity; details pending verification)
Registered in
Hong Kong
APAC prepaid card program; details blocked from automated verification.
Every external source used on this page, with the date we fetched it. Methodology: how we verify. Sources disappear or change - if a link is dead, tell us via contact. Quoted text is the verbatim excerpt this review cites.
“Cashback is issued in USDs. - Usage : USDs can only be used for future card transactions. They cannot be used to purchase cards, withdrawn as cash, or transferred.”
“Once funds are deposited for card use, custody sits with RedotPay and its card partners. The account can be restricted or frozen if compliance checks fail, and”
“under several recognised regulatory frameworks , including VASP authorisation in Argentina , MSB registration in Canada , a FinCEN-registered MSB status in the”
A niche virtual-card tool for online media buying with crypto funding - now with a named operator (ADV Summit Advisors Limited, TCI) and documented fees. Usable for its purpose, but the 3% cashback is a Private-subscription ad-spend benefit paid as subscription credit, and the regulated issuing side remains unnamed. Poor as a general spending card; keep balances minimal.
A non-custodial stablecoin wallet with a Wirex-issued prepaid card: documented 1-8% cashback tiers in stablecoins, free virtual card, Apple Pay/Google Pay and up to 5% APY. The rewards are real but tiered behind $COCA balances, the official pages contradict each other on cashback rate and card network, and the independent FX spread measurement undercuts the 0% FX marketing. Verify the current card terms in-app before loading.
Full KYC8% backphysical card0% FX
0% load · 0% FX · 8% back
EUR 30,000 (plus EUR 75,000/quarter and EUR 100,000/6-month caps)Crypto-native 38 d ago
A real, shipping product from a well-funded Solana ecosystem team (Solayer Labs), now branded Solayer Pay after launching as the Emerald Card in April 2025. Virtual + physical Visa-compatible cards, Apple/Google Pay, ATM access, USDC-funded. Weaknesses: fee stack ($20/yr + 1% top-up + $0.15/txn + FX), no standing cashback (points with future promised utility), heavy restrictions (17 US states, most of Western Europe, CA/AU/NZ/IN/KR excluded), issuer not published, and 'non-custodial' marketing that contradicts its own hot/cold wallet security description. Fees/limits transparency is actually good (dedicated docs) — more than most competitors publish.


No comments yet - be the first. No account needed; the anti-spam proof runs in your browser.